How Net Worth Tracking Actually Works
Net worth is one of the simplest ways to measure your overall financial position, yet many people rarely calculate it.
Unlike income, which tells you how much money comes in, or a budget, which shows how money is being spent, net worth measures what you own after subtracting what you owe.
Tracking it regularly can help you understand whether your financial position is improving, identify areas that need attention and make better decisions about saving, investing and debt.
The calculation itself is straightforward. The more important part is understanding what belongs in the calculation, how to track changes and what the numbers actually mean.
For a broader overview of the tools and systems that can bring these different areas together, see this complete money management system.
What Is Net Worth?
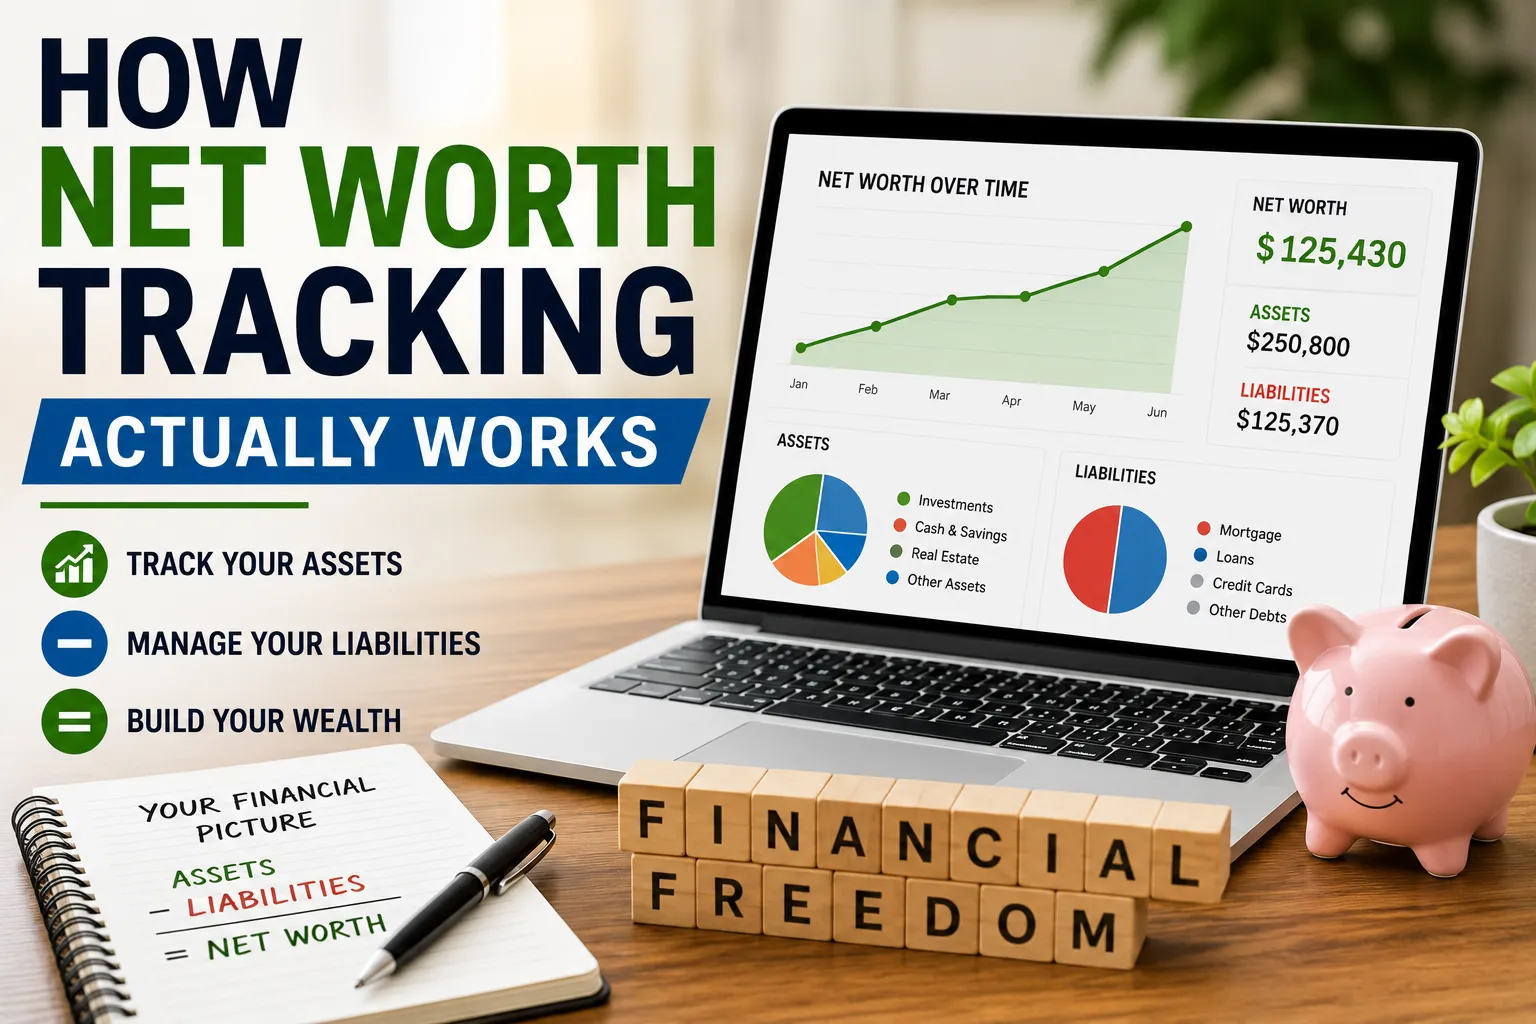
Net worth is the value of your assets minus your liabilities.
The basic formula is:
Net Worth = Total Assets − Total Liabilities
Assets are things you own that have financial value. Liabilities are debts or obligations you owe to other people or institutions.
For example, imagine someone has:
- $25,000 in savings and investments
- A car worth $15,000
- A home worth $250,000
- $180,000 remaining on a mortgage
- $10,000 in other debts
Their total assets would be $290,000.
Their total liabilities would be $190,000.
Their net worth would therefore be $100,000.
The same principle applies whether someone has a few hundred dollars or several million dollars in assets.
Assets Make Up One Side of the Equation
The first step in tracking net worth is identifying everything you own that has meaningful financial value.
Common assets include:
- Cash
- Bank account balances
- Savings
- Stocks
- Bonds
- Mutual funds
- Exchange-traded funds
- Retirement accounts
- Business interests
- Real estate
- Vehicles
- Valuable personal property
Not every possession needs to be included.
A person could theoretically assign a value to every piece of furniture, electronic device or item of clothing, but doing so usually adds complexity without providing much useful information.
Most people benefit from focusing on assets that have significant financial value and can reasonably be estimated.
Cash and Bank Accounts Are Easy to Track
Cash is among the simplest assets to include.
Add the current balances of relevant:
- Checking accounts
- Savings accounts
- Money-market accounts
- Cash holdings
- Other deposit accounts
Use current balances rather than the amount you originally deposited.
If you have multiple accounts, keeping them listed separately can make it easier to identify where your money is held.
Investments Need Current Values
Investment accounts should generally be valued based on their current market value rather than how much you originally paid.
For example, if you bought shares for $10,000 and they are now worth $13,000, the asset value used in your net-worth calculation is approximately $13,000.
This means your net worth can change even when you have not deposited or withdrawn any money.
Investment prices fluctuate, so changes in net worth do not necessarily mean you have saved or spent money.
Retirement Accounts Count Too
Retirement savings are generally assets and should be included in a net-worth calculation.
Depending on your financial system, these could include:
- Employer-sponsored retirement plans
- Individual retirement accounts
- Pension-related investment accounts
- Personal retirement investments
The balance should normally reflect the current value of the account.
Taxes and withdrawal restrictions can affect how much of the balance you could actually access, so keeping notes about these limitations can provide additional context.
Your Home Can Be an Asset
If you own a home, its estimated current market value can be included among your assets.
The important point is to use the home’s estimated current value rather than simply the amount you originally paid.
For example, if you purchased a property for $200,000 and it is now reasonably estimated to be worth $280,000, the asset side of your calculation would use the newer estimate.
However, the property’s mortgage must also be included as a liability.
The difference between the home’s value and the remaining mortgage balance represents the approximate equity you have in the property.
Vehicles Can Be Included, But Be Consistent
Vehicles are assets because they have resale value.
However, their value generally declines over time.
If you include a vehicle in your net-worth calculation, use a realistic estimate of its current market value rather than its original purchase price.
There is also an argument for excluding ordinary vehicles and personal possessions if they are not important to your financial planning.
The key is consistency.
If you include them one month and exclude them the next, changes in your net worth can become misleading.
Business Ownership Can Be More Complicated
Business interests can represent a substantial portion of someone’s net worth.
The challenge is determining their current value.
A private business does not have a continuously quoted market price in the same way that a publicly traded stock does.
Its value may depend on revenue, profits, assets, debts, industry conditions and what a potential buyer might reasonably pay.
For personal tracking, a conservative estimate may be more useful than an overly optimistic valuation.
If the business represents a major portion of your wealth, professional valuation advice may be appropriate for more formal financial planning.
Liabilities Are the Other Side of the Equation
After listing your assets, identify everything you owe.
Common liabilities include:
- Mortgages
- Credit-card balances
- Personal loans
- Auto loans
- Student loans
- Business debt
- Tax obligations
- Other outstanding debts
Use the current amount owed rather than the original amount borrowed.
A $300,000 mortgage taken out several years ago might have a remaining balance of $250,000 today.
That $250,000 is the relevant liability for your current net-worth calculation.
Debt Reduction Can Increase Net Worth
One of the useful features of net-worth tracking is that it shows the effect of debt repayment.
Suppose you have $20,000 in savings and $15,000 of debt.
Your net worth is $5,000.
If you pay off $5,000 of debt using $5,000 of savings, your assets fall to $15,000 while your debt falls to $10,000.
Your net worth remains $5,000.
But as you continue paying down the debt using new income, your net worth can increase.
This illustrates an important point: moving money between accounts does not automatically increase wealth. Building assets or reducing liabilities is what changes net worth over time.
Net Worth Is Different From Income
A high income does not automatically produce a high net worth.
Someone earning a large salary may spend most of it and accumulate significant debt.
Another person with a more modest income may consistently save, invest and avoid unnecessary borrowing.
Over time, the second person’s net worth could become substantially higher.
Income is therefore an important input into financial progress, but it is not the same thing as wealth.
Net Worth Is Different From Cash Flow
Cash flow measures money moving in and out over a period.
For example:
Income − Expenses = Cash Flow
Net worth, on the other hand, represents your financial position at a particular point in time.
The two measurements work together.
If your income consistently exceeds your expenses, you have more money available to save, invest or repay debt. Those actions can eventually improve your net worth.
Tracking both can provide a much clearer picture of your finances than tracking either one alone.
For a closer look at the other side of this relationship, see how expense tracking and cash flow tools help manage household finances.
Why Track Net Worth?
Regular net-worth tracking can help answer questions that a monthly budget cannot.
For example:
- Am I becoming financially stronger?
- Is my debt declining?
- Are my investments growing?
- Am I saving enough?
- How much equity do I have in my home?
- Is my spending preventing wealth accumulation?
- How much of my wealth depends on one asset?
These questions become easier to answer when you have a history of your financial position.
Net Worth Gives You a Long-Term Perspective
Monthly financial numbers can be noisy.
Investment markets rise and fall. Property values change. Large annual expenses can temporarily reduce savings.
A longer net-worth history helps put these short-term fluctuations into perspective.
Instead of focusing entirely on whether your investments gained or lost money this month, you can examine whether your overall financial position has improved over several years.
This makes net-worth tracking particularly useful for long-term financial planning.
How Often Should You Track Net Worth?
There is no universal schedule.
Some people prefer monthly tracking because it provides regular feedback without requiring constant attention.
Others may find quarterly tracking more practical.
Daily tracking is generally unnecessary because investment prices and account balances can fluctuate significantly from one day to another.
For most households, monthly or quarterly tracking provides a useful balance between awareness and simplicity.
Use the Same Method Every Time
Consistency is essential.
If you value your house using one method in January and a completely different method in June, the resulting change may say more about your valuation method than your actual financial progress.
Try to use the same sources and assumptions whenever possible.
For example:
- Bank balances: current statements
- Investments: account balances
- Mortgage: current loan balance
- Vehicle: consistent valuation source
- Property: reasonable market estimate
- Business interests: consistent valuation method
The goal is not perfect precision.
The goal is a useful and reasonably consistent measurement.
Keep a Net-Worth Statement
A simple net-worth statement can organize the information.
For example:
| Category | Value |
|---|---|
| Cash and savings | $20,000 |
| Investments | $45,000 |
| Retirement accounts | $30,000 |
| Home | $250,000 |
| Vehicle | $15,000 |
| Total assets | $360,000 |
| Mortgage | $180,000 |
| Other debt | $20,000 |
| Total liabilities | $200,000 |
| Net worth | $160,000 |
Keeping historical versions allows you to compare your financial position over time.
For households that want to make this process easier, keeping financial records organized can also make recurring net-worth reviews much simpler.
Spreadsheets Can Be Enough
You do not necessarily need specialized software to track net worth.
A spreadsheet can contain columns for:
- Account or asset
- Current value
- Previous value
- Change
- Liability
- Net worth
- Date
A simple spreadsheet can be particularly useful because you control the information and can customize the categories.
It also makes it easier to calculate longer-term changes.
Net-Worth Tracking Apps Can Automate the Process
Financial tracking tools can sometimes connect to bank, investment and other accounts and automatically update balances.
This can reduce manual work.
However, automation comes with considerations around account access, security, privacy and data accuracy.
Before connecting financial accounts to a third-party service, understand what information it collects, how it protects data and what permissions it requires.
Automation should make tracking easier without causing you to lose awareness of where your financial information is going.
Don’t Confuse Net Worth With Spendable Money
Net worth is not the same as money you can immediately spend.
Suppose a person owns a home worth $500,000 but has only $10,000 in cash.
Their net worth could be substantial, but they do not have $500,000 available for everyday expenses.
Similarly, retirement accounts may have restrictions or tax consequences associated with withdrawals.
This is why net worth should be considered alongside liquidity.
A household can have a high net worth and still experience cash-flow problems.
Track Liquid Net Worth Separately if Useful
Some people find it helpful to maintain a second measure called liquid net worth.
This generally focuses on assets that can be accessed relatively easily, such as cash and certain investments, while excluding assets that are difficult or costly to convert into cash.
The exact definition can vary.
Tracking both total net worth and liquid net worth can provide a clearer picture of overall wealth and financial flexibility.
Watch for Concentration Risk
A net-worth statement can reveal how dependent your financial position is on one asset.
For example, if most of your net worth comes from your home, your financial situation may be heavily influenced by property values.
If most of your wealth is tied to your employer’s stock, your finances could be particularly vulnerable to problems at that company.
Net-worth tracking therefore does more than measure wealth. It can expose concentration risks that might otherwise be difficult to see.
Net Worth Can Fall Even When You Do Everything Right
A decline in net worth is not automatically evidence of poor financial management.
Investment markets can fall.
Property values can decline.
A major purchase can temporarily reduce savings.
Unexpected expenses can increase debt.
The important question is what caused the change.
If your investment portfolio falls during a broad market downturn while your savings habits and debt management remain strong, the decline may be temporary.
Understanding the reason behind a change is often more useful than reacting emotionally to the number itself.
Look at Trends Instead of Isolated Numbers
One month’s net worth is only a snapshot.
A longer series of measurements can reveal trends.
For example, you might discover that:
- Debt is steadily declining
- Savings are increasing
- Investment assets are growing
- Housing equity is rising
- Spending is preventing consistent savings
These patterns can help you identify whether your financial strategy is working.
Separate Market Growth From Your Own Contributions
Your net worth can increase for different reasons.
Suppose your investment portfolio grows by $10,000.
That increase could result from:
- New contributions
- Investment gains
- Both
Separating these factors can help you understand how much progress is coming from your own saving versus changes in asset prices.
Over time, this distinction becomes increasingly important as investment assets become a larger part of your financial position.
Track Net Worth Without Becoming Obsessed With It
Financial tracking is useful when it helps you make better decisions.
It becomes less useful when every small change causes anxiety or leads to impulsive decisions.
Investment markets can move significantly over short periods.
Checking your net worth repeatedly during market volatility may encourage emotional reactions that have little to do with your long-term financial plan.
For most people, regular reviews are more productive than constant monitoring.
Use Net Worth to Set Financial Goals
Once you know your current net worth, you can use it as a starting point for broader goals.
For example, your objectives might include:
- Eliminating high-interest debt
- Building an emergency fund
- Increasing retirement savings
- Buying a home
- Growing investment assets
- Building business wealth
- Reaching financial independence
If emergency savings are one of your priorities, a separate guide on how much emergency savings families should have can help put that goal into context.
The goal should not simply be to make the net-worth number larger.
The purpose is to build a financial position that supports the life you want.
Don’t Compare Your Net Worth Too Closely With Other People
Net worth varies enormously based on age, income, family circumstances, inheritance, housing markets and many other factors.
Comparing your number with a friend, colleague or online personality can therefore be misleading.
A better comparison is your current financial position against your own previous position.
If your debt is falling, savings are increasing and assets are growing in a sustainable way, you may be making meaningful progress regardless of what someone else reports.
The Real Value of Tracking Net Worth
Net-worth tracking is ultimately a way of turning a complicated financial life into a number that can be monitored over time.
The calculation is simple:
Assets minus liabilities equals net worth.
But the insights can be significant.
Tracking your balances can show whether debt is shrinking, savings are growing, investments are accumulating and your overall financial position is moving in the direction you want.
The number will not tell you everything about your finances, and it will naturally fluctuate. Used alongside a budget, cash-flow plan and appropriate financial goals, however, it can become one of the clearest ways to see whether your financial decisions are gradually building wealth.
The most useful net-worth number is not today’s figure—it is the direction your financial position is moving over time.