How to Calculate Household Net Worth From Assets and Liabilities
Household finances can be difficult to understand when income, bills, savings, loans and other financial commitments are spread across different accounts. One of the simplest ways to get a clearer picture is to calculate household net worth.
Net worth provides a snapshot of what a household owns after subtracting what it owes. Unlike monthly income or expenses, it focuses on the household’s overall financial position.
Understanding how to calculate net worth can help families measure progress, identify financial weaknesses and make more informed decisions about saving, borrowing and long-term financial goals.
For a broader look at how net worth tracking fits into an overall financial management system, see this complete money management system.
What Is Household Net Worth?
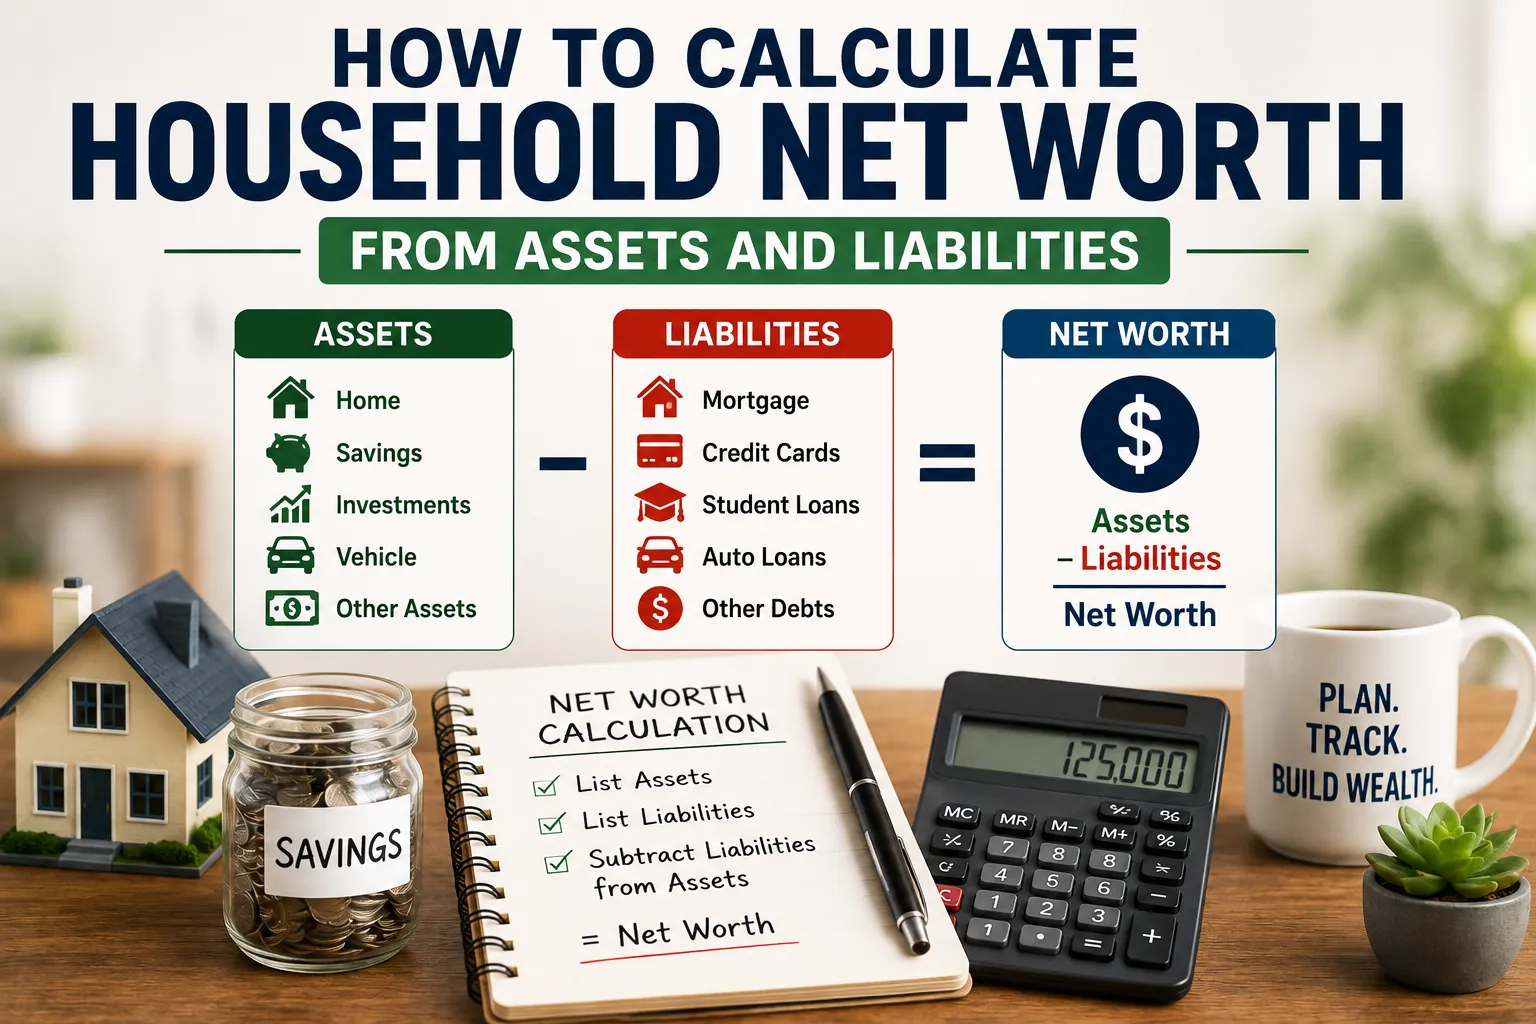
Household net worth is the difference between the total value of a household’s assets and the total amount of its liabilities.
The basic formula is:
Net Worth = Total Assets − Total Liabilities
If a household owns $300,000 worth of assets and has $180,000 in liabilities, its net worth is:
$300,000 − $180,000 = $120,000
A positive net worth means the household’s assets are worth more than its debts. A negative net worth means its liabilities exceed its assets.
Net worth is not a measure of how much money a family earns. A household can have a high income but relatively little net worth if it has substantial debt and limited savings.
Likewise, a household with a modest income may build significant net worth over time by accumulating assets and managing debt carefully.
Understanding Household Assets
Assets are things a household owns that have financial value.
Common household assets include:
- Cash
- Checking account balances
- Savings accounts
- Retirement accounts
- Investment accounts
- Stocks and bonds
- Real estate
- Vehicles
- Valuable personal property
- Business interests
- Certain insurance or financial assets
The goal is to estimate the current value of these assets rather than simply adding up what was originally paid for them.
Cash and Bank Accounts
Cash is usually among the easiest assets to calculate.
Include current balances in:
- Checking accounts
- Savings accounts
- Money market accounts
- Certificates of deposit
- Physical cash, if significant
Use current balances rather than the amount deposited originally.
Investments
Investment assets can include:
- Stocks
- Bonds
- Mutual funds
- Exchange-traded funds
- Brokerage accounts
- Retirement investments
For publicly traded investments, use their current market value.
For example, if a household owns investments currently worth $40,000, that $40,000 belongs on the asset side of the net worth calculation.
Market values fluctuate, so investment-based net worth will naturally change over time.
Retirement Accounts
Retirement savings should generally be included when calculating household net worth.
Examples include:
- Employer-sponsored retirement accounts
- Individual retirement accounts
- Pension-related assets where an appropriate valuation is available
- Other retirement investment accounts
A retirement account may not be immediately available for spending without taxes, penalties or other restrictions, but it still represents an asset.
Real Estate
A primary residence can be one of the largest assets a household owns.
Use a reasonable estimate of the property’s current market value, rather than its original purchase price.
For example:
Estimated home value: $350,000
If the household still owes $240,000 on the mortgage, the home’s contribution to net worth is approximately:
$350,000 − $240,000 = $110,000
That $110,000 represents home equity.
Vehicles
Cars, motorcycles and other vehicles can also be included as assets.
However, vehicles generally depreciate, so their current market value may be substantially lower than the purchase price.
A household that paid $35,000 for a car several years ago should not automatically count the vehicle as a $35,000 asset.
Instead, use a realistic estimate of what the vehicle could currently sell for.
Personal Property
Households may also own valuable items such as:
- Jewelry
- Collectibles
- Valuable equipment
- Antiques
- Artwork
- Certain electronics
Not every household possession needs to be listed individually.
Ordinary household items can be difficult to value and may have limited resale value. Including them at inflated estimates can make a net worth calculation less useful.
For a practical household balance sheet, focus on assets with meaningful financial value.
Understanding Household Liabilities
Liabilities are debts and other financial obligations that a household owes.
Common liabilities include:
- Mortgages
- Auto loans
- Student loans
- Credit card balances
- Personal loans
- Medical debts
- Business-related debts
- Other outstanding loans
Use the current outstanding balance, not the original amount borrowed.
Mortgage Debt
If a home is worth $400,000 and the household owes $275,000 on the mortgage, the mortgage liability is $275,000.
The home contributes approximately $125,000 to net worth through home equity.
Auto Loans
Suppose a vehicle is currently worth $20,000 but the household owes $24,000 on its auto loan.
The vehicle and its loan together produce:
$20,000 − $24,000 = −$4,000
This is negative equity.
Negative equity is important because it demonstrates why simply counting the value of vehicles without accounting for associated loans can produce a misleading picture.
Credit Card Debt
Credit card balances should be included as liabilities.
If a household has:
- Card A: $2,000
- Card B: $1,500
- Card C: $500
Total credit card liabilities equal:
$4,000
Even if the household pays its credit cards every month, any balance currently owed should generally be included in a point-in-time net worth calculation.
A Simple Household Net Worth Example
Consider a hypothetical household with the following assets:
| Asset | Current Value |
|---|---|
| Checking and savings | $25,000 |
| Investments | $60,000 |
| Retirement accounts | $90,000 |
| Home | $350,000 |
| Vehicle | $25,000 |
| Other valuable assets | $10,000 |
| Total Assets | $560,000 |
Now consider its liabilities:
| Liability | Current Balance |
|---|---|
| Mortgage | $240,000 |
| Auto loan | $15,000 |
| Credit cards | $4,000 |
| Personal loan | $6,000 |
| Total Liabilities | $265,000 |
The household’s net worth would be:
$560,000 − $265,000 = $295,000
That means the household has an estimated net worth of $295,000.
How to Calculate Net Worth Step by Step
Calculating net worth does not require complicated financial software.
Step 1: List Every Major Asset
Create a list of financial and physical assets that have meaningful value.
Include bank accounts, investments, retirement savings, real estate, vehicles and other significant assets.
Step 2: Determine Current Values
Use current balances or reasonable current market estimates.
Avoid relying on what an asset originally cost.
Step 3: Add the Assets
Add the values together to determine total household assets.
Step 4: List Every Significant Debt
Write down outstanding balances for mortgages, auto loans, credit cards, student loans and other debts.
Step 5: Add the Liabilities
Add the current balances together to determine total liabilities.
Step 6: Subtract Liabilities From Assets
Use the formula:
Total Assets − Total Liabilities = Net Worth
The resulting figure is your household’s estimated net worth.
Net Worth Is Different From Cash Flow
Net worth and cash flow answer different financial questions.
Cash flow looks at money coming into and leaving the household over a period of time.
Net worth looks at the household’s financial position at a particular point in time.
For example, a household might earn $8,000 per month and spend $7,500. Its monthly cash flow is positive by $500.
But that tells you very little about whether the household has substantial assets or significant debt.
Net worth provides the broader balance-sheet perspective.
Households that want to understand this relationship in more detail can also explore how expense tracking and cash flow tools help manage household finances.
Why Net Worth Can Fall Even When Finances Are Healthy
A declining net worth does not automatically mean a household is making poor financial decisions.
Asset values can change.
For example:
- Investment markets can fall.
- Property values can decline.
- Vehicles can depreciate.
- Business valuations can change.
At the same time, debt balances may decline as loans are repaid.
This means net worth should generally be viewed as a long-term financial indicator, rather than something that must increase every month.
For a broader explanation of how net-worth measurements change over time and how to interpret those changes, see how net worth tracking actually works.
How Debt Affects Net Worth
Debt has a direct effect on net worth because liabilities are subtracted from assets.
Consider two households that each own $200,000 in assets.
Household A
- Assets: $200,000
- Liabilities: $50,000
- Net worth: $150,000
Household B
- Assets: $200,000
- Liabilities: $175,000
- Net worth: $25,000
Their asset totals are identical, but their financial positions are dramatically different because of their debt levels.
Reducing high-cost debt can therefore be an important part of building net worth.
What Counts as a Good Net Worth?
There is no single net worth number that is appropriate for every household.
Age, income, location, family size, homeownership status, career stage and financial goals can all affect what a healthy financial position looks like.
Comparing your household with someone else’s can therefore be misleading.
A more useful approach is to monitor your own progress over time.
For example:
| Year | Assets | Liabilities | Net Worth |
|---|---|---|---|
| Year 1 | $250,000 | $200,000 | $50,000 |
| Year 2 | $285,000 | $195,000 | $90,000 |
| Year 3 | $320,000 | $185,000 | $135,000 |
The household’s net worth increased even though the change was driven by a combination of asset growth and debt reduction.
How Households Can Build Net Worth
There are two fundamental ways to increase net worth:
Increase assets or reduce liabilities.
In practice, households can work on both.
Build Emergency Savings
Maintaining accessible savings can help households handle unexpected expenses without relying heavily on high-interest debt.
For more guidance on setting an appropriate emergency savings target, see how much emergency savings families should have.
Invest Consistently
Long-term investing can allow savings to grow through investment returns and compounding, although investments can lose value and are not guaranteed.
Pay Down Expensive Debt
High-interest consumer debt can make it difficult to build wealth.
Reducing expensive debt can improve the household’s balance sheet while also lowering future interest costs.
Build Home Equity Carefully
Mortgage payments can gradually increase home equity as the loan balance declines.
However, homeownership also involves taxes, insurance, maintenance and other costs, so rising home equity should not be considered the only measure of housing affordability.
Increase Savings Over Time
Regularly directing part of household income toward savings and investments can gradually increase financial assets.
The important factor is consistency rather than trying to predict exactly which asset will perform best.
How Often Should You Calculate Net Worth?
Many households can benefit from calculating net worth once or twice a year.
Checking too frequently can make normal market fluctuations appear more significant than they are.
An annual calculation provides a useful snapshot for evaluating longer-term progress.
Households experiencing major financial changes—such as buying a home, paying off a major loan or changing investment strategies—may choose to review their balance sheet more often.
Keep a Net Worth Statement
A simple spreadsheet can make the process much easier.
Create separate sections for:
Assets
- Bank accounts
- Investments
- Retirement accounts
- Real estate
- Vehicles
- Other significant assets
Liabilities
- Mortgage
- Auto loans
- Credit cards
- Student loans
- Personal loans
- Other debts
Then include:
Total Assets − Total Liabilities = Net Worth
Keeping historical records allows households to see whether their financial position is improving over several years.
The Bigger Picture Behind Net Worth
Household net worth is more than a single number. It is a snapshot of the relationship between what a family owns and what it owes.
A household can improve its financial position by accumulating productive assets, maintaining adequate savings, reducing expensive debt and making borrowing decisions carefully.
The most useful calculation is therefore not necessarily the one that produces the biggest number today. It is the one that helps a household understand its financial position clearly and track whether its decisions are moving that position in the right direction over time.