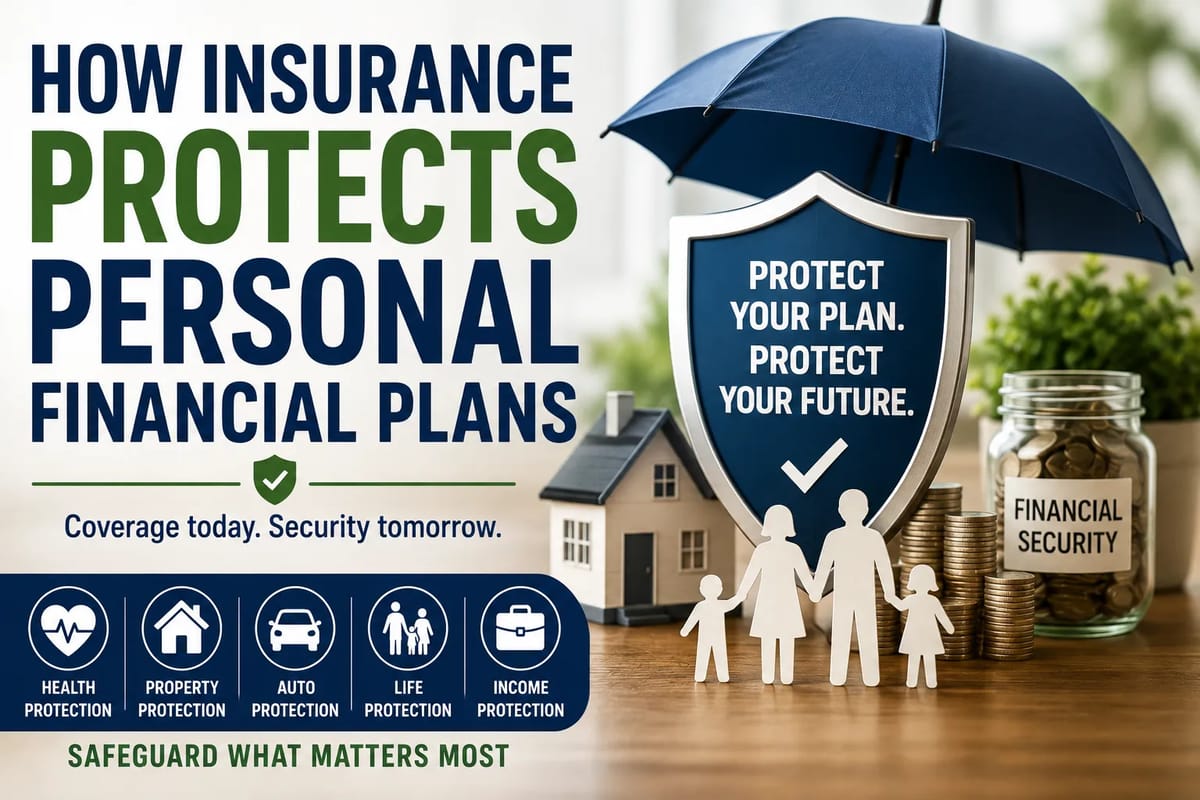
How Insurance Protects Personal Financial Plans
A financial plan can look perfectly sound on paper and still be vulnerable to one unexpected event.
A serious illness, major car accident, house fire, disability, lawsuit, or premature death can create expenses large enough to disrupt years of saving and investing. Insurance is designed to help manage some of those risks by transferring certain financial losses to an insurer in exchange for a premium.
The National Association of Insurance Commissioners describes insurance as a way to manage financial risks and explains that coverage can help prevent individuals from having to pay the entire cost of covered losses themselves.
Insurance is therefore not simply another monthly bill. When appropriately selected, it can be part of a broader financial strategy designed to protect income, assets, savings, and long-term goals.
For households evaluating coverage options, how to evaluate insurance policies and providers provides a more detailed framework for comparing policies, costs, coverage and insurers.
What Insurance Does in a Financial Plan
At its simplest, insurance creates a financial safety net around risks that could otherwise be difficult to absorb.
You pay a premium to maintain coverage. If a covered event occurs, the insurer pays according to the terms, limits, exclusions, deductibles, and conditions of the policy.
For example, consider a homeowner with $50,000 in savings.
A major covered property loss could potentially cost far more than that amount. Without insurance, the homeowner might have to use savings, borrow money, sell investments, or delay other financial goals.
With appropriate insurance, the financial impact may be substantially reduced, although the policyholder may still have deductibles and uncovered expenses.
That is the central role insurance can play in financial planning: protecting the assets and income you have worked to build.
Insurance and Financial Risk
Every financial plan contains risk.
Some risks are relatively easy to absorb.
A $100 unexpected expense may be inconvenient but manageable.
A $100,000 expense is very different.
Financial planning becomes stronger when households distinguish between risks they can comfortably pay themselves and risks that could cause severe financial damage.
Insurance can be particularly useful for risks that are:
- Potentially expensive
- Difficult to predict
- Infrequent
- Capable of disrupting long-term financial goals
The objective is not to insure every possible inconvenience.
It is to protect against losses that could seriously damage your financial position.
Insurance Is Not the Same as Savings
Insurance and savings serve different purposes.
An emergency fund is money you own and can access for unexpected expenses.
Insurance is a contractual arrangement that provides financial protection against specified risks.
The two can work together.
For example, an emergency fund might cover a deductible, temporary income disruption, or smaller repair, while insurance helps address a much larger covered loss.
The CFPB recommends maintaining emergency savings because unexpected expenses can otherwise force households to rely on credit cards or loans.
Why Emergency Savings Still Matter
Having insurance does not eliminate the need for cash reserves.
Most insurance policies do not pay every dollar associated with an unexpected event.
Depending on the policy, you may have:
- Deductibles
- Copayments
- Coinsurance
- Coverage limits
- Exclusions
- Waiting periods
- Uninsured expenses
An emergency fund can provide the liquidity needed to handle these costs.
This is why insurance and emergency savings are complementary rather than interchangeable.
Health Insurance Can Protect a Financial Plan
Medical expenses can be unpredictable and potentially substantial.
Health insurance can help reduce the financial burden associated with covered healthcare expenses, depending on the policy and local healthcare system.
Without appropriate coverage, a major medical event could require a household to use:
- Emergency savings
- Investments
- Retirement assets
- Credit
- Borrowed money
The exact structure of health insurance varies significantly between countries and policies, so households should understand what their plan actually covers.
Life Insurance Protects Dependents
Life insurance serves a different purpose from property or health coverage.
Its primary financial role is protecting people who depend on the insured person’s income or financial support.
If a household’s primary earner dies unexpectedly, surviving family members may face:
- Lost income
- Housing costs
- Debt
- Childcare expenses
- Education costs
- Funeral expenses
- Other long-term financial obligations
Life insurance can provide a death benefit to named beneficiaries, subject to the policy’s terms.
The NAIC describes life insurance as an important part of long-term family financial planning because it can provide financial support to beneficiaries after the policyholder dies.
Who May Need Life Insurance?
Life insurance is generally more relevant when other people depend financially on you.
This may include:
- Parents
- Married couples
- Single parents
- Business owners
- People supporting relatives
- Households with significant debts
- People whose income is essential to family expenses
Someone with no financial dependents and substantial assets may have a different need for life insurance than someone supporting several family members.
The right amount of coverage depends on individual circumstances.
Life Insurance Can Protect Long-Term Goals
Consider a household planning to pay for a child’s education while also repaying a mortgage.
If one parent’s income disappears unexpectedly, both goals could be jeopardized.
Appropriate life insurance can help provide resources for the surviving family to continue pursuing those goals.
This is why life insurance should be considered alongside:
- Income
- Debt
- Savings
- Investments
- Education costs
- Housing
- Retirement planning
rather than as an isolated product.
Term Life Insurance Can Cover Specific Financial Obligations
Term life insurance provides coverage for a specified period.
It can be useful when financial responsibilities are particularly high during certain years.
For example, someone may want coverage while:
- Children are financially dependent
- A mortgage remains outstanding
- A spouse depends on their income
- A business obligation exists
The NAIC notes that term life insurance can be appropriate when coverage is needed for a specific period or financial obligation, such as a mortgage.
Permanent Life Insurance Is Different
Permanent life insurance generally provides coverage beyond a specific term and may include a cash-value component, depending on the policy.
These policies can be more complicated than term insurance.
The financial objectives, costs, guarantees, investment components, surrender provisions, and tax treatment can vary.
Anyone considering permanent life insurance should understand the policy’s actual costs and mechanics rather than assuming that every policy works like a savings or investment account.
Disability Insurance Protects Earning Power
For many working adults, their most valuable financial asset is not their bank balance.
It is their ability to earn income.
A person earning $60,000 annually could potentially earn millions over a multi-decade career.
An illness or injury that prevents someone from working can therefore create a much larger financial risk than many people realize.
Disability insurance can provide income replacement under qualifying circumstances, depending on the policy.
This can help protect:
- Mortgage payments
- Rent
- Food expenses
- Utilities
- Debt payments
- Savings contributions
- Family expenses
Your Income Is an Asset
Financial planning often focuses heavily on assets such as investments, property, and savings.
But future income is also economically valuable.
A young professional with limited savings may have relatively few financial assets today but decades of potential earnings ahead.
Protecting that earning ability can therefore be an important part of financial planning.
Auto Insurance Protects More Than the Vehicle
Auto insurance is not simply about repairing a damaged car.
Liability coverage can protect against financial losses associated with injuries or property damage for which the insured is legally responsible, subject to the policy and applicable law.
Without appropriate liability protection, a serious accident could potentially expose personal assets and future income to substantial claims.
This makes liability coverage an important part of protecting a broader financial plan.
Homeowners Insurance Protects a Major Asset
For many households, the home is their largest asset.
Homeowners insurance can protect the structure and personal property against covered losses while also providing liability protection in covered circumstances.
The NAIC notes that homeowners insurance can provide protection for the home, personal belongings, and personal liability, while mortgage lenders commonly require homeowners coverage.
A homeowner should therefore think about insurance as part of asset protection rather than simply a requirement attached to a mortgage.
Renters Need Insurance Too
Renters do not own the building, but they still own personal belongings.
Furniture, electronics, clothing, appliances, and other possessions can have significant replacement costs.
Renters insurance may also provide liability protection and other coverage depending on the policy.
The fact that a person does not own their home does not mean they have nothing worth protecting.
Property Insurance Does Not Cover Everything
One of the most important insurance lessons is that a policy is not a blanket guarantee against every possible loss.
Coverage depends on the policy.
Certain risks may require separate insurance or endorsements.
For example, the NAIC notes that flood and earthquake coverage may be separate from standard homeowners insurance depending on the circumstances.
This is why simply having an insurance policy is not enough.
You need to understand what it actually covers.
Liability Insurance Protects Against More Than Property Damage
A lawsuit can create a financial problem even when your own property is unharmed.
Liability insurance can help protect against covered claims involving injuries or property damage for which you are legally responsible.
This can be especially important for households with significant assets.
In some circumstances, additional liability coverage such as an umbrella policy may be appropriate.
The right amount depends on individual risk and local insurance options.
Insurance Can Protect Investments From Forced Selling
Imagine an investor has built a substantial retirement portfolio.
A major uninsured expense occurs.
The investor needs cash immediately and sells investments to pay the bill.
If the market happens to be down, the investor may lock in losses and reduce future growth potential.
Appropriate insurance can sometimes reduce the probability that an unexpected event forces a household to liquidate long-term investments at an inconvenient time.
This is one of the less obvious ways insurance can support investment planning.
Insurance Can Protect Retirement Savings
Retirement accounts are designed for long-term financial needs.
Using retirement assets to pay for an unexpected emergency can interfere with decades of compounding.
Insurance cannot prevent every financial shock, but appropriate coverage can reduce the size of certain shocks.
That can help keep retirement savings focused on their intended purpose.
Insurance and Debt Protection
Unexpected expenses can also lead to new debt.
A household without sufficient insurance might use:
- Credit cards
- Personal loans
- Home-equity borrowing
- Other forms of credit
to pay for a major loss.
The CFPB notes that households without emergency savings may rely on credit cards or loans after financial shocks, potentially creating longer-lasting debt.
Insurance can sometimes reduce the amount that needs to be borrowed after a covered event.
Insurance Costs Money, So It Must Be Balanced
Insurance provides protection, but premiums are an expense.
Buying every available policy can create another financial problem: too much of the household budget goes toward insurance.
The objective is therefore not maximum insurance.
It is appropriate insurance.
A good financial plan balances:
- Premiums
- Deductibles
- Coverage limits
- Exclusions
- Financial resources
- Risk exposure
- Household responsibilities
Understand the Deductible
A deductible is the amount you generally pay before the insurer pays its share of a covered claim.
For example, suppose a covered loss results in $10,000 of eligible damage and your deductible is $1,000.
If the policy covers the entire remaining amount, you would generally be responsible for the first $1,000 and the insurer would pay according to the policy terms.
The exact claim calculation depends on the policy.
Higher deductibles can sometimes reduce premiums, but they also mean you need more cash available after a loss.
Choose a Deductible You Can Afford
A low premium is not automatically the best deal.
If the deductible is so high that you could not afford it after an emergency, the policy may provide less practical protection than you expect.
Before choosing a policy, ask:
“If I had to make a claim tomorrow, could I comfortably pay the deductible?”
If the answer is no, reconsider the coverage structure.
Don’t Underinsure Valuable Assets
Underinsurance can create a false sense of security.
A homeowner may have insurance but discover after a major loss that the coverage limit is insufficient to rebuild the property or replace important belongings.
Review coverage when circumstances change.
Important changes can include:
- Renovations
- New purchases
- Home improvements
- Rising construction costs
- Changes in household size
- New valuable possessions
The NAIC recommends paying attention to whether homeowners coverage is based on actual cash value or replacement cost because the two can produce different claim outcomes.
Understand Replacement Cost and Actual Cash Value
These terms can have significant financial consequences.
Actual cash value generally considers depreciation when determining the value of damaged property.
Replacement cost generally focuses on the cost to replace or repair with materials of like kind and quality, subject to policy terms and limits.
The distinction can affect how much money is available after a covered loss.
Read your policy rather than assuming every type of coverage pays the same way.
Review Insurance After Major Life Changes
Insurance needs are not permanent.
A policy that made sense five years ago may no longer fit your circumstances.
Review coverage after events such as:
- Marriage
- Divorce
- Birth of a child
- Death in the family
- New employment
- Significant income changes
- Buying a home
- Paying off a mortgage
- Starting a business
- Major renovations
- Acquiring valuable property
Changes in your financial responsibilities can change the amount and type of protection you need.
Don’t Automatically Buy More Coverage
A common misconception is that more insurance is always better.
More coverage generally means higher premiums.
Instead, consider the actual financial consequences of the risk.
Ask:
- How likely is this event?
- How much could it cost?
- Could I pay for it myself?
- Would it threaten my financial goals?
- Is insurance available at a reasonable cost?
- What are the policy exclusions?
These questions help distinguish important coverage from unnecessary expense.
Know Which Risks You Can Self-Insure
Some risks are small enough to handle using your own savings.
For example, you may not need insurance for every inexpensive item you own.
If a loss would be annoying but financially manageable, paying for insurance may not provide enough value to justify the premium.
The more serious question is whether you could comfortably absorb the loss without damaging your broader financial plan.
Review Your Policies Annually
An annual insurance review can be useful.
Check:
- Coverage limits
- Deductibles
- Premiums
- Beneficiaries
- Exclusions
- Policy terms
- Major changes in your assets
- Major changes in your income
- New financial responsibilities
The review does not necessarily mean changing your policies.
Sometimes the best decision is to confirm that existing coverage remains appropriate.
Compare Policies Carefully
When comparing insurance, avoid focusing only on the premium.
Two policies with similar prices can offer very different protection.
Compare:
- Coverage limits
- Deductibles
- Exclusions
- Waiting periods
- Claims procedures
- Optional coverage
- Renewal terms
- Provider reputation
- Financial strength where relevant
For a detailed comparison process, including how to assess costs, coverage, providers and policy features, see how to evaluate insurance policies and providers.
The cheapest policy may not be the most valuable policy.
Consider the Insurer’s Financial Strength
An insurance policy is a promise to pay eligible claims according to its terms.
The financial condition of the insurer therefore matters.
Insurance regulators use financial standards to monitor insurers’ ability to meet obligations. The NAIC’s risk-based capital framework, for example, is designed to identify potentially weakly capitalized insurers and facilitate regulatory action.
Consumers can also research insurers through their local insurance regulator and other reputable sources.
Keep Policy Documents Accessible
Knowing that you have insurance is not enough during an emergency.
Keep accessible records of:
- Policy numbers
- Insurer contact details
- Agent information
- Coverage summaries
- Beneficiary information
- Renewal dates
- Claims procedures
Digital backups can be useful, provided they are stored securely.
Know How to File a Claim
If a covered event occurs, documentation can make the claims process easier.
Depending on the policy, useful records may include:
- Photographs
- Videos
- Receipts
- Repair estimates
- Police reports
- Medical documentation
- Ownership records
The NAIC recommends documenting losses and submitting appropriate evidence when filing certain property claims.
Follow your insurer’s instructions and keep copies of submitted documents.
Insurance Should Work With Your Budget
Insurance premiums should be included in the household budget.
Treating them as unexpected expenses can make financial planning more difficult.
Create a complete list of recurring insurance costs, such as:
- Health
- Auto
- Home
- Renters
- Life
- Disability
- Other relevant coverage
Then consider how those costs fit alongside savings, debt repayment, and investing.
Don’t Sacrifice Emergency Savings for Premiums
Insurance is valuable, but a household still needs liquidity.
If premiums consume so much income that there is no room for emergency savings, the overall financial plan may become fragile.
The goal is to build several layers of protection:
Insurance → Emergency savings → Investments → Long-term assets
Each layer serves a different purpose.
Use Insurance to Protect Financial Goals
A strong financial plan usually contains goals such as:
- Buying a home
- Paying education costs
- Building retirement savings
- Starting a business
- Supporting children
- Becoming debt-free
- Leaving an inheritance
Insurance can help prevent an unexpected event from forcing those goals to be abandoned.
For example, disability coverage may protect income while life insurance may protect dependents. Homeowners insurance can protect a major asset, while liability coverage can help protect wealth against certain claims.
Insurance and Estate Planning
Life insurance can also interact with estate planning.
Beneficiary designations can determine who receives policy proceeds after death, subject to the policy and applicable law.
Because estate and tax rules differ significantly between jurisdictions, beneficiaries and policy ownership should be reviewed alongside other estate-planning documents where appropriate.
Insurance and Taxes
Insurance can also have tax implications.
The treatment of:
- Premiums
- Benefits
- Cash values
- Employer-provided coverage
- Business insurance
- Life insurance proceeds
can vary depending on the type of policy and the jurisdiction.
Do not assume that an insurance payment is automatically taxable or tax-free.
For significant policies or complex situations, professional tax advice may be appropriate.
Business Owners Have Additional Risks
Entrepreneurs may need to consider risks that employees do not face.
Depending on the business, these can include:
- Property damage
- Liability claims
- Professional errors
- Business interruption
- Employee injuries
- Cyber incidents
- Loss of a key person
Business insurance can therefore be part of protecting both the business and the owner’s personal financial plan.
The specific coverage required depends heavily on the industry and jurisdiction.
Insurance Can Protect a Family’s Standard of Living
A financial plan is not only about accumulating money.
It is also about maintaining a reasonable quality of life when circumstances change.
Insurance can help preserve:
- Housing
- Transportation
- Access to healthcare
- Family income
- Business continuity
- Financial independence
That protective function can be particularly valuable during periods when a household has limited financial flexibility.
Common Insurance Mistakes
Several mistakes can weaken the financial protection a policy is supposed to provide.
Buying Based Only on Price
The cheapest premium may come with lower limits or broader exclusions.
Ignoring Exclusions
A policy only covers the risks and circumstances specified in its contract.
Choosing a Deductible You Cannot Afford
A policy may be difficult to use if the deductible is financially overwhelming.
Forgetting to Update Beneficiaries
Life changes can make old beneficiary designations inappropriate.
Failing to Review Coverage
Your assets and responsibilities can change substantially over time.
Assuming Every Loss Is Covered
Insurance policies contain exclusions, conditions, limits, and definitions.
Letting Coverage Lapse
A missed payment can potentially result in loss of coverage depending on the policy and applicable rules.
A Simple Insurance Planning Checklist
Use this checklist as a starting point:
- List the major financial risks your household faces.
- Identify risks you could comfortably pay yourself.
- Identify losses that could seriously damage your finances.
- Review existing insurance coverage.
- Check deductibles.
- Check coverage limits.
- Review exclusions.
- Confirm life insurance beneficiaries.
- Consider whether your income needs protection.
- Review health coverage.
- Review property and liability coverage.
- Compare premiums periodically.
- Keep emergency savings available.
- Update policies after major life changes.
- Keep policy documents accessible.
Insurance Should Support, Not Replace, Financial Planning
Insurance is only one part of a comprehensive financial strategy.
A household also needs to consider:
- Budgeting
- Emergency savings
- Debt management
- Retirement savings
- Investing
- Tax planning
- Estate planning
- Income growth
Insurance protects against certain risks; it does not create wealth by itself.
The strongest plans use insurance to protect the financial progress created through these other strategies.
Financial protection also extends beyond insurance. Households should consider how they protect themselves from fraudulent financial activity and deceptive schemes; how to protect your family from financial scams covers that complementary side of financial risk management.
Protect the Plan You Spend Years Building
Personal financial planning is often described in terms of accumulation: save money, invest consistently, reduce debt, and build assets.
But financial security also depends on protecting what has already been built.
A major uninsured loss can undo years of progress surprisingly quickly. Appropriate insurance can reduce that risk by shifting certain potentially devastating costs to an insurer, subject to the policy’s terms and limitations.
The right strategy is not to buy every type of insurance available. It is to identify the risks that could seriously disrupt your household, determine which ones you can reasonably absorb yourself, and insure the risks that could otherwise derail important financial goals.
Insurance works best when it is treated as part of a larger financial plan: emergency savings provide liquidity, investments build wealth, and insurance helps protect the income and assets that make those long-term goals possible.