How to Teach Children About Money
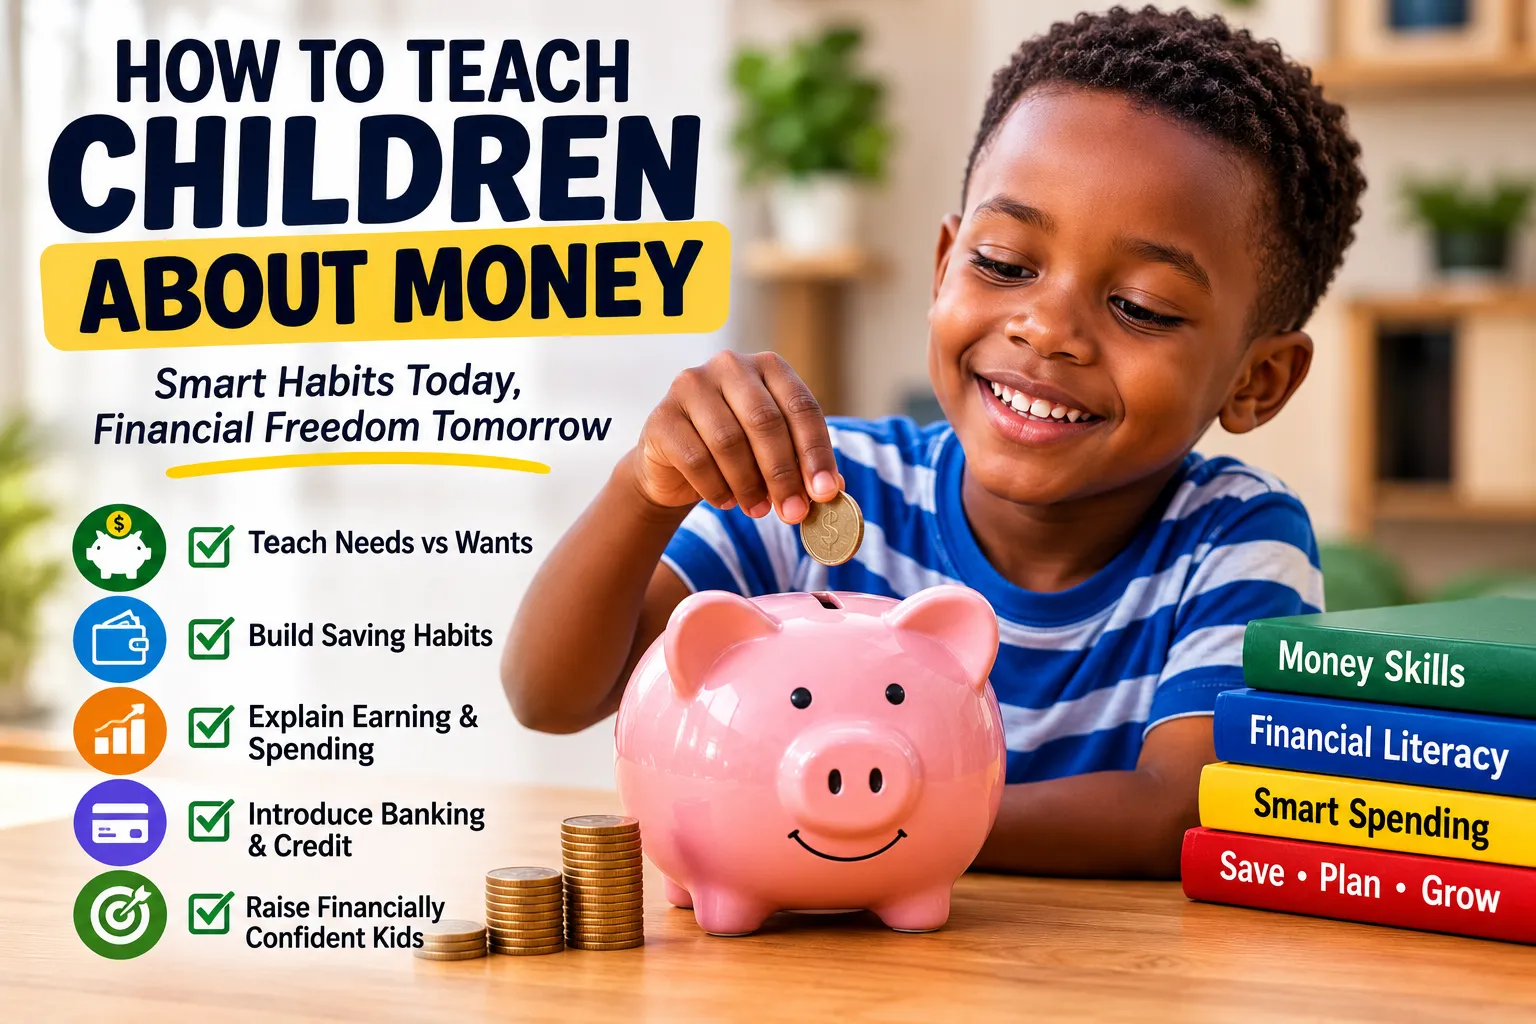
Teaching children about money is one of the most valuable life skills parents and caregivers can provide. Children learn about spending, saving and earning long before they understand concepts such as interest rates, credit scores or investing.
The goal isn’t to turn young children into financial experts. It is to help them develop healthy habits and understand that money is a limited resource that can be planned, prioritized and used thoughtfully.
With age-appropriate conversations and practical experiences, children can gradually learn how money works and become more confident managing it as they grow.
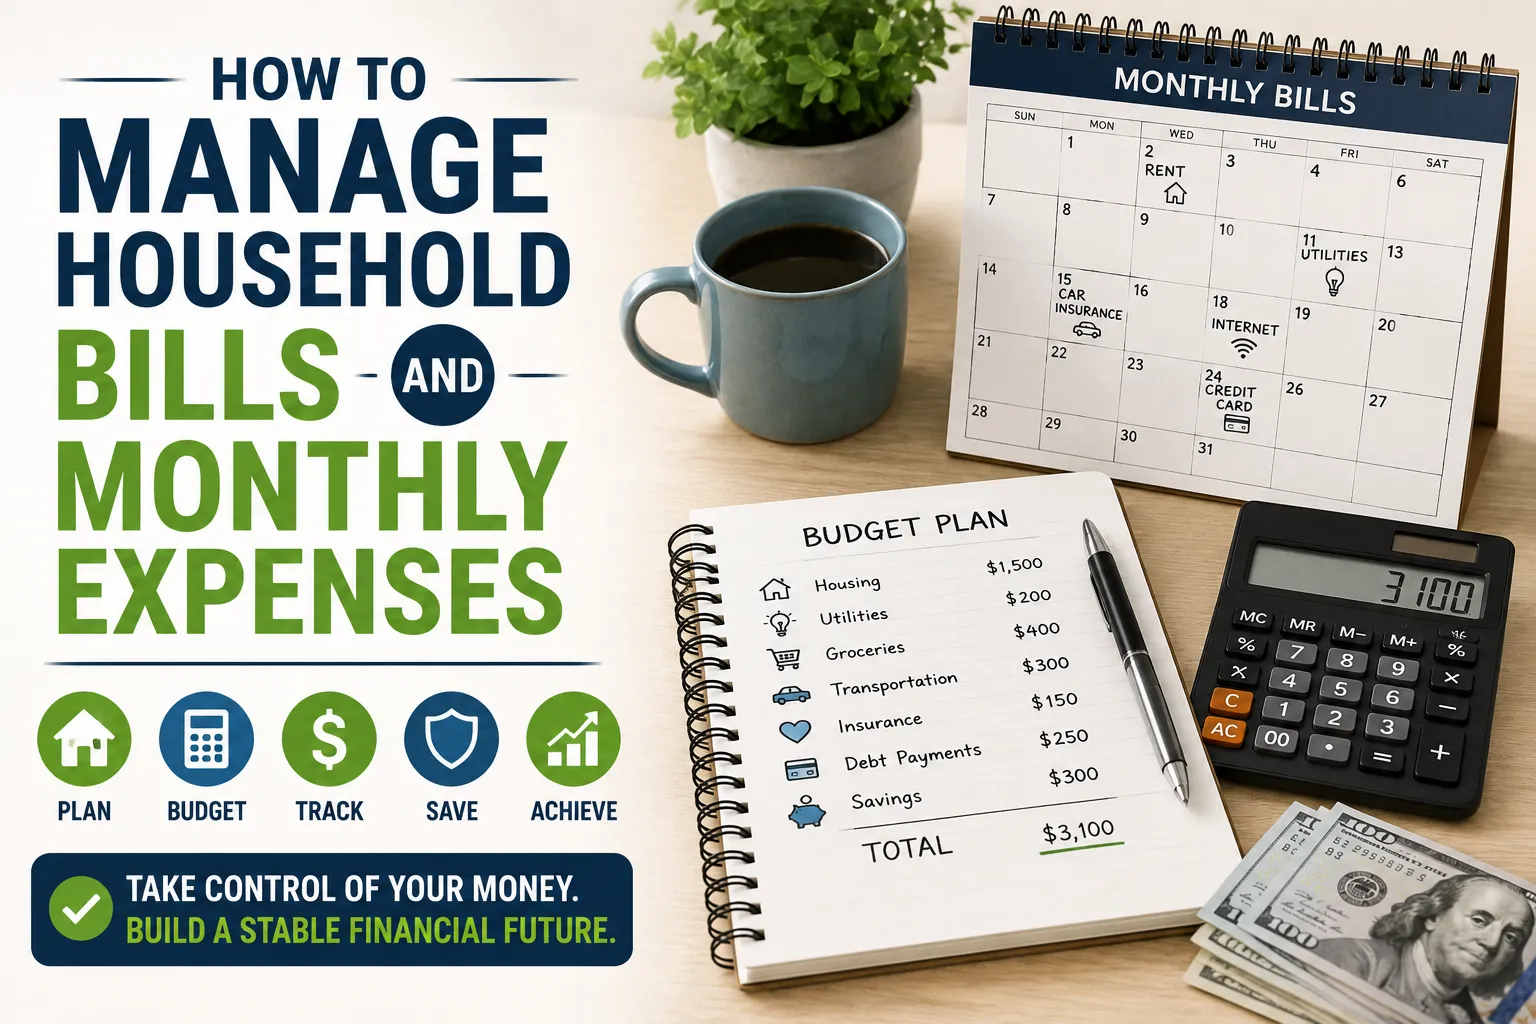
One of the best ways to make these lessons practical is to connect them to the way money is actually managed at home. A family budget can give children an age-appropriate example of how income, household needs, saving and spending decisions fit together.
Why Children Need to Learn About Money
Children see adults using money every day. They watch parents pay bills, shop for groceries, order products online and make decisions about what the family can afford.
Without guidance, however, children may develop inaccurate assumptions about money.
Financial education can help children understand that:
- Money is earned through work or other legitimate sources.
- People have different financial circumstances.
- Spending decisions involve trade-offs.
- Saving requires delaying some purchases.
- Needs and wants are different.
- Borrowing money creates responsibilities.
- Advertising is designed to influence purchasing decisions.
- Small financial habits can have long-term effects.
Learning these ideas early can make financial concepts easier to understand later.
Start With Simple Money Conversations
Financial education doesn’t need to begin with a formal lesson.
Everyday situations provide natural opportunities to talk about money.
For example, while grocery shopping, you might explain why you’re comparing prices. When planning a family outing, you can discuss how the cost of different activities affects the overall budget.
Simple questions can also encourage children to think about financial decisions:
- “Do you think we need this or want it?”
- “How could we save enough to buy that?”
- “Which option costs less?”
- “What would happen if we spent all our money today?”
- “Would you rather buy one expensive item or several smaller ones?”
These conversations help children understand the reasoning behind financial decisions rather than simply hearing rules such as “we can’t afford it.”
Teach the Difference Between Needs and Wants
One of the most important financial concepts for children is the difference between needs and wants.
Needs are things people generally require for basic living, such as:
- Food
- Safe housing
- Basic clothing
- Essential healthcare
- Education
- Basic transportation in many circumstances
Wants are things that can improve enjoyment or convenience but aren’t essential for basic needs.
Examples might include:
- Toys
- Video games
- Restaurant meals
- Designer clothing
- Entertainment subscriptions
- The latest electronic devices
The distinction isn’t always absolute. What counts as a need can depend on a family’s circumstances.
The important lesson is that money should be prioritized rather than spent automatically.
Give Children Opportunities to Handle Money
Children learn effectively through experience.
Giving them an opportunity to manage a small amount of money can make abstract financial concepts more tangible.
Depending on their age, this could involve:
- A small allowance
- Money received as a gift
- Earnings from age-appropriate tasks
- A savings jar
- A supervised bank account
The amount isn’t as important as the opportunity to make decisions.
A child who receives a small amount of money can begin learning what happens when they spend everything immediately versus saving part of it.
Use Three Simple Money Categories
A useful way to introduce money management is to divide money into three broad categories:
Spend
This is money available for things the child chooses to purchase.
Save
This money is set aside for a larger future goal.
Give
This category can introduce children to generosity and helping others when appropriate for the family’s values and circumstances.
You can use physical jars, envelopes or a simple chart for younger children.
For older children, a supervised savings account or digital budgeting system may make more sense.
Teach Children How Saving Works
Saving is easier to understand when children have a specific goal.
Instead of simply telling a child to “save money,” help them identify something they want to purchase.
For example:
“The bicycle costs $120. You already have $40. If you save $10 each week, how many weeks will it take to reach your goal?”
This turns saving into a practical exercise involving mathematics, patience and planning.
Children can learn that reaching a goal often requires delaying smaller purchases.
Make Saving Visible
Young children often find money easier to understand when they can physically see their progress.
A transparent savings jar can work particularly well because the child can watch the amount grow.
Other approaches include:
- Savings charts
- Goal thermometers
- Sticker trackers
- Envelopes
- Simple spreadsheets for older children
- Child-friendly banking apps where appropriate
The visual representation reinforces the connection between saving regularly and reaching a goal.
Teach Delayed Gratification
Delayed gratification is an important part of financial discipline.
Children naturally tend to focus on what they want immediately. Learning to wait for something can help them understand the value of planning.
One simple exercise is to establish a waiting period before certain non-essential purchases.
For example:
“Let’s wait three days before deciding whether you still want it.”
For older children, the waiting period might be longer.
This doesn’t mean children should never make spontaneous purchases. Instead, it teaches them that not every desire needs to become an immediate purchase.
Explain How Earning Money Works
Children should understand that money doesn’t simply appear when someone uses a card or taps a phone.
Explain that people generally receive money through activities such as:
- Employment
- Running a business
- Providing professional services
- Creating products
- Investments and other legitimate financial assets
For younger children, age-appropriate household responsibilities can help demonstrate the relationship between effort and compensation.
However, families should distinguish between ordinary responsibilities and optional paid tasks.
For example, basic responsibilities such as cleaning up after oneself may simply be part of contributing to the household. Additional age-appropriate jobs could potentially provide an opportunity to earn money.
The specific approach should fit the family’s values and circumstances.
Don’t Make Money Conversations Only About Restriction
Financial education can become confusing if children hear only negative messages such as:
- “We can’t afford that.”
- “Money doesn’t grow on trees.”
- “That’s too expensive.”
- “We never have enough money.”
Children also need to learn that money can be used positively.
Money can help people:
- Meet essential needs
- Reach important goals
- Support education
- Build businesses
- Prepare for emergencies
- Enjoy experiences
- Help others
- Create greater financial flexibility
The goal is not to make children afraid of spending. It is to teach them how to make thoughtful decisions.
Teach Children About Budgeting
As children become older, introduce the concept of a budget.
A budget is essentially a plan for how available money will be used.
For a teenager, a simple monthly budget might include:
| Category | Example Amount |
|---|---|
| Saving | $40 |
| Spending | $30 |
| Giving | $10 |
| Transportation | $20 |
| Total | $100 |
The exact numbers aren’t important.
The lesson is that money is limited and allocating it in advance can prevent accidental overspending.
Parents can make the lesson more realistic by showing how households also have to plan for expenses that don’t occur every month. For example, families can explain the idea behind budgeting for irregular expenses and why saving a little at a time can make larger future bills easier to handle.
Let Children Make Small Financial Mistakes
One of the most powerful financial lessons can come from making a relatively harmless mistake.
Suppose a child spends all their money on snacks and then realizes they don’t have enough left for something they’ve been saving toward.
Instead of immediately replacing the money, use the situation as a learning opportunity.
Ask:
- “How do you feel about the decision?”
- “What would you do differently next time?”
- “How could you reach your goal now?”
- “What could you plan before spending next time?”
Small mistakes made under supervision can teach lessons that are difficult to communicate through lectures.
Teach Comparison Shopping
Children can learn that the first price they see isn’t necessarily the best option.
While shopping, compare:
- Price
- Quantity
- Quality
- Durability
- Features
- Warranty
- Cost per unit
- Whether the item is actually needed
For older children, introduce the concept of unit pricing.
For example, if one package contains 500 grams and another contains 750 grams, comparing only the sticker prices doesn’t necessarily tell you which is cheaper per unit.
This teaches children to evaluate value rather than simply looking for the lowest headline price.
Explain Advertising and Impulse Buying
Children are surrounded by marketing.
Advertisements can make products appear exciting, necessary or socially important.
Teach children to ask:
“Do I want this because I need it, or because an advertisement made it look appealing?”
Older children can learn about:
- Influencer marketing
- Sponsored content
- Product placement
- Discounts
- Limited-time offers
- Brand loyalty
- Online recommendations
- Social pressure
Understanding how marketing works can help children become more thoughtful consumers.
Teach Children About Online Money
Modern children may interact with money without ever seeing physical cash.
They may encounter:
- Mobile payments
- Digital wallets
- Online shopping
- In-app purchases
- Subscription services
- Gaming purchases
- Contactless payments
- Digital banking
This creates an important lesson:
Digital money is still real money.
A tap on a screen doesn’t make a purchase free.
Parents can explain that every digital transaction represents money being transferred from one account to another.
Discuss In-App Purchases
Games and apps can provide particularly useful financial lessons.
Children may encounter:
- Virtual currencies
- Premium features
- Cosmetic items
- Subscription upgrades
- Randomized digital purchases
- Limited-time offers
Explain that virtual items still cost real money.
Parents should also use appropriate parental controls and account settings to reduce the risk of unauthorized purchases.
Introduce Banking Basics
Older children can gradually learn what a bank does.
Explain that banks and other financial institutions can provide services such as:
- Holding deposits
- Facilitating payments
- Providing loans
- Offering savings products
- Providing debit or credit cards
- Supporting electronic transfers
A teenager may benefit from having a supervised account that allows them to practice managing money.
The goal is to make the transition to independent financial management less intimidating.
Explain Interest in Simple Terms
Interest can initially seem complicated, but the basic concept is straightforward.
When you keep money in certain savings products, the financial institution may pay interest.
When you borrow money, you generally pay interest to the lender.
A simple example can illustrate the difference.
If a child saves $100 in an account that earns interest, the balance may gradually increase.
If they borrow $100 and must repay $110, the additional $10 represents part of the cost of borrowing.
This introduces an important principle:
Interest can work for you when you’re saving and against you when you’re borrowing.
The actual rates, compounding frequency and account terms vary by institution.
Teach Children About Credit
Credit is an important concept for teenagers and young adults to understand before they begin borrowing.
Explain that credit allows someone to obtain money or goods now and repay later under agreed terms.
Examples include:
- Credit cards
- Personal loans
- Student loans
- Auto loans
- Mortgages
Children should understand that borrowing isn’t free.
The total cost can include:
- Interest
- Fees
- Penalties
- Other charges
A person who borrows should understand the repayment obligations before agreeing to the debt.
Explain Why Credit Scores Matter
Older teenagers can begin learning that lenders and other businesses may use credit information to assess someone’s borrowing history.
Depending on the country, credit scoring systems can consider factors such as:
- Payment history
- Amount of debt
- Credit utilization
- Length of credit history
- Types of credit accounts
- Recent applications
Credit scoring systems vary by country and provider, so children should learn the principles rather than memorize a particular scoring formula.
The key lesson is simple:
Borrowing responsibly and paying obligations on time can help build a stronger financial history.
Teach Children About Debt
Not all debt should be treated identically.
Some borrowing may help someone acquire an asset or fund an opportunity, while other debt may finance purchases that provide little lasting value.
Children don’t need complicated financial theories at first.
Start with three questions:
- Why are you borrowing?
- How much will you repay in total?
- Can you comfortably make the required payments?
This framework can help children understand that the amount borrowed is not necessarily the same as the amount ultimately repaid.
Introduce Emergency Savings
As children become teenagers, introduce the idea of an emergency fund.
An emergency fund is money set aside for unexpected expenses.
Examples might include:
- An urgent repair
- Replacing an essential item
- Unexpected transportation costs
- Emergency travel
- Other unplanned expenses
The specific amount someone needs depends on their circumstances.
The broader lesson is that financial planning isn’t only about achieving exciting goals. It is also about preparing for unexpected problems.
Explain the Difference Between Saving and Investing
Children often hear the words “saving” and “investing” used interchangeably.
They aren’t the same.
Saving generally focuses on preserving money and keeping it accessible for shorter-term goals.
Investing involves putting money into assets with the expectation of potential growth over time, while accepting the possibility of losing value.
Investment examples can include:
- Stocks
- Bonds
- Mutual funds
- Exchange-traded funds
- Real estate
Investments carry different levels of risk.
Children should understand that higher potential returns generally come with greater uncertainty and that investments can lose money.
Teach the Power of Compound Growth
Compound growth is one of the most useful financial concepts to introduce as children get older.
In simple terms, compounding means that returns can themselves generate additional returns over time.
For example, if an investment earns a return and those gains remain invested, future returns can potentially apply to both the original amount and previous gains.
This is one reason starting to save or invest early can be powerful.
However, actual investment returns are uncertain, and examples used for education should not be interpreted as guaranteed results.
Talk About Financial Goals
Children should learn that financial goals can be:
Short-Term Goals
Examples include saving for a book, game or outing.
Medium-Term Goals
Examples include saving for a bicycle, computer or larger purchase.
Long-Term Goals
For older teenagers and young adults, long-term goals might include education, transportation, housing or retirement.
Breaking large goals into smaller steps makes them easier to understand.
Teach Generosity and Financial Responsibility
Money education isn’t only about accumulation.
Children can also learn about generosity and responsible use of resources.
Depending on the family’s values, this could involve:
- Donating part of their savings
- Helping someone in need
- Supporting a community project
- Giving thoughtful gifts
- Volunteering time rather than money
The important lesson is that financial success can involve how money is used, not simply how much someone accumulates.
Be Honest About Family Finances Without Oversharing
Children don’t necessarily need to know every detail of a family’s financial situation.
However, completely avoiding money conversations can make financial matters seem mysterious.
Parents can share age-appropriate information about:
- How household bills work
- Why families create budgets
- Why some purchases require planning
- How saving helps with large expenses
- Why people prepare for emergencies
The level of detail should increase as children mature.
Age-by-Age Money Lessons
Different ages call for different financial concepts.
| Age | Useful Money Lessons |
|---|---|
| 3–5 | Recognizing coins and notes, counting, needs versus wants |
| 6–8 | Saving, spending, simple choices, earning |
| 9–12 | Budgeting, comparison shopping, financial goals |
| 13–15 | Banking, digital payments, advertising, interest |
| 16–18 | Credit, debt, investing basics, taxes, budgeting |
| 18+ | Independent banking, credit management, insurance, investing, long-term planning |
These are general guidelines rather than strict rules. A child’s maturity, experience and family circumstances should determine when specific concepts are introduced.
Common Mistakes Parents Make When Teaching Money
Making Money a Taboo Subject
If children never hear adults discuss money, they may enter adulthood without understanding basic financial decisions.
Giving Too Much Information Too Quickly
Complex financial concepts can overwhelm younger children. Introduce ideas gradually.
Paying for Everything
Children who never have to make spending decisions don’t get many opportunities to practice financial judgment.
Rescuing Children From Every Mistake
Automatically replacing money after every poor decision can remove an important learning opportunity.
Using Money as a Punishment
Financial education works better when money is presented as a tool for making choices rather than simply as a reward or punishment.
Focusing Only on Saving
Saving is important, but children also need to understand spending, earning, giving, borrowing and investing.
Setting a Poor Example
Children pay attention to what adults do, not just what they say.
How Parents Can Lead by Example
One of the most effective ways to teach financial literacy is to demonstrate responsible behavior.
Children can observe adults:
- Comparing prices
- Planning purchases
- Saving regularly
- Paying bills on time
- Avoiding unnecessary debt
- Preparing for emergencies
- Discussing financial goals
- Reviewing household expenses
You don’t need to be financially perfect.
In fact, explaining how you correct a financial mistake can sometimes provide a more useful lesson than pretending that every decision is perfect.
Simple Money Activities for Children
Financial lessons can be turned into practical activities.
Create a Savings Challenge
Give children a specific goal and help them track progress.
Plan a Small Shopping Trip
Give them a fixed amount and ask them to decide how to use it.
Compare Products
Look at two similar products and calculate which offers better value.
Create a Family Budget Example
Use fictional amounts to demonstrate how income might be divided among expenses, savings and other priorities.
Start a Money Journal
Older children can record income, spending and savings goals.
Calculate a Savings Goal
Ask how long it would take to reach a target by saving a certain amount each week.
These activities make financial concepts concrete and memorable.
Help Children Understand Planned Large Purchases
As children get older, they can also learn why families don’t necessarily buy every expensive item immediately.
A major purchase may require saving in advance, comparing alternatives and deciding whether the purchase fits within the household’s priorities.
For teenagers, this can become a practical exercise. If they want an expensive phone, computer, bicycle or other item, parents can help them calculate how much they need to save each week or month.
The same principle applies to adults managing larger household purchases. Learning how families can plan financially for major purchases can help children eventually understand why large expenses require preparation rather than impulsive spending.
Teach Children That Education Can Have Financial Costs
Education is another useful real-world example of long-term financial planning.
Children can gradually learn that education may involve expenses beyond tuition, including supplies, books, transportation, technology, activities and other costs.
The lesson doesn’t need to focus on exact future amounts. Instead, children can learn that important long-term goals often require planning years in advance.
Families can eventually discuss how families can plan and save for education costs as an example of how saving today can support a future goal.
The Most Important Money Lessons to Teach
If you want to keep financial education simple, focus on a few foundational principles:
- Money is limited.
- Needs usually come before wants.
- Saving requires planning and patience.
- Earning money involves value and effort.
- Borrowing creates obligations.
- Interest can increase both savings and debt.
- Advertising can influence spending decisions.
- Digital payments still represent real money.
- Small financial choices can compound over time.
- Good money management is a skill that improves with practice.
These principles provide a foundation children can build on throughout their lives.
Building Financial Confidence One Lesson at a Time
Teaching children about money isn’t a single conversation or a one-time lesson. It’s an ongoing process that evolves as children grow, encounter new financial situations and become more independent.
Start with simple concepts such as counting, saving and distinguishing needs from wants. Later, introduce budgeting, banking, credit, debt, investing and long-term financial planning.
The objective isn’t to raise children who never make a financial mistake. It’s to help them develop the knowledge and confidence to make thoughtful decisions, learn from mistakes and understand the consequences of their choices.
The earlier children begin practicing these skills in age-appropriate ways, the more prepared they can be to manage money responsibly when they eventually have to make financial decisions on their own.