How Housing Costs Affect Family Finances
Housing is one of the largest expenses in most household budgets. Whether a family rents an apartment, owns a home with a mortgage, lives in a smaller property or pays for housing through another arrangement, the cost of keeping a roof over one’s head affects almost every other financial decision.
When housing costs are manageable, families generally have more room to save, invest, handle emergencies and spend on everyday needs. When housing consumes too much of the household budget, even a reasonable income can feel stretched.
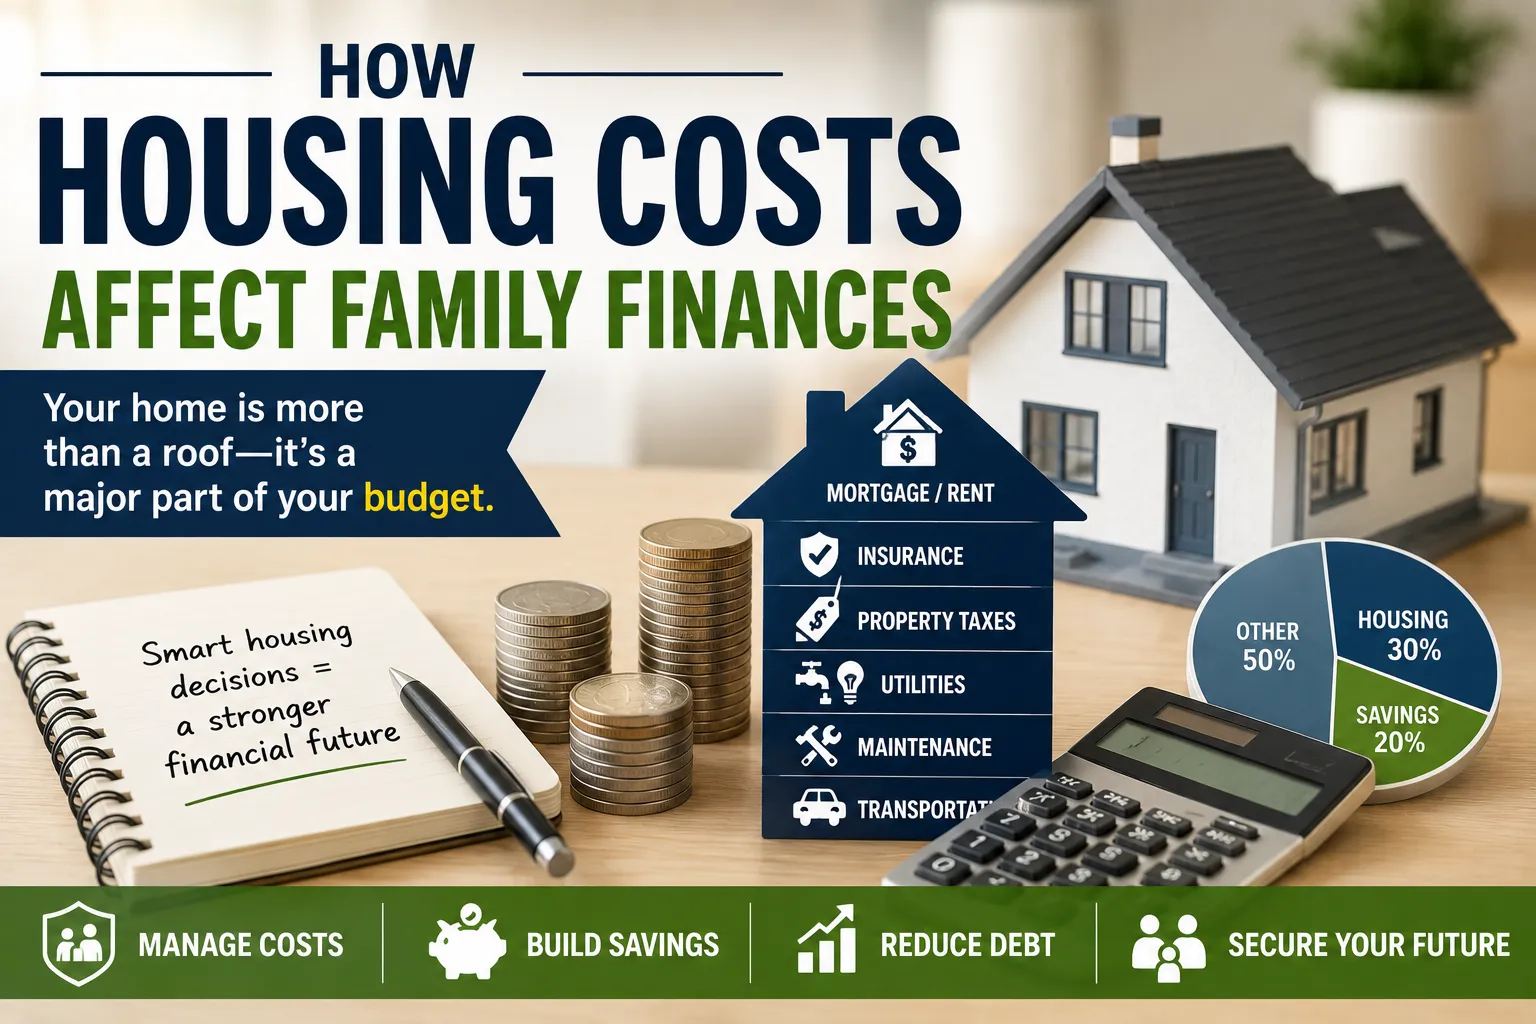
The impact goes beyond the monthly rent or mortgage payment. Property taxes, insurance, utilities, maintenance, transportation and repairs can all add to the real cost of housing.
Understanding these costs can help families make better decisions about where they live, how much they spend and how housing fits into their broader financial goals.
A housing decision should therefore be considered as part of the family’s overall financial plan. Families can start by understanding how to build a family budget and then determining how housing fits alongside other household priorities.
What Counts as a Housing Cost?
Housing costs include much more than rent or a mortgage.
For renters, expenses may include:
- Monthly rent
- Security deposits
- Renters insurance
- Utilities
- Parking
- Maintenance-related fees
- Pet fees
- Application or administrative charges
For homeowners, the list can be considerably longer:
- Mortgage principal
- Mortgage interest
- Property taxes
- Homeowners insurance
- Mortgage insurance
- HOA or association fees
- Utilities
- Repairs
- Maintenance
- Landscaping
- Security systems
- Pest control
Some costs are predictable every month, while others appear irregularly.
That distinction is important when creating a household budget. An annual insurance bill, major repair or school expense can create a problem if the family has not prepared for it in advance. Planning for irregular family expenses can make these less predictable costs easier to manage.
Why Housing Has Such a Large Financial Impact
Housing is different from many other expenses because it is difficult to eliminate quickly.
A family can reduce restaurant spending, cancel subscriptions or postpone buying clothes.
It is much harder to suddenly reduce a $2,000 monthly rent payment or mortgage.
Moving can be expensive and disruptive, while selling a home can involve substantial transaction costs.
This makes housing a relatively fixed commitment for many households.
When the housing payment is too large, families may have limited options for reducing expenses elsewhere.
Housing Costs Affect More Than the Housing Budget
Imagine a household bringing home $6,000 per month.
If housing costs $1,500, the family has $4,500 left for everything else.
If housing costs $2,400, only $3,600 remains.
The difference is:
$2,400 − $1,500 = $900 per month
Over a year, that becomes:
$900 × 12 = $10,800
That additional $10,800 could otherwise have gone toward savings, debt repayment, childcare, education, investments or other family priorities.
This illustrates why housing decisions can have effects far beyond the housing category itself.
The 30% Rule Is Only a Starting Point
A commonly referenced guideline suggests spending no more than around 30% of household income on housing.
The idea can be useful as a starting point, but it does not work equally well for every family.
Consider two households with identical incomes.
Family A
- High student-loan payments
- Two vehicle loans
- Expensive childcare
- Significant medical expenses
Family B
- No consumer debt
- Low transportation costs
- No childcare expenses
- Significant savings
Both families could have the same income but very different affordable housing budgets.
This is why families should look at their entire financial picture, rather than relying on a single percentage.
Gross Income and Take-Home Pay Are Different
Housing affordability calculations sometimes use gross income, which is income before taxes and other deductions.
Household budgeting should also consider take-home pay.
For example, a household may earn $8,000 per month before taxes but receive substantially less after:
- Income taxes
- Retirement contributions
- Health insurance
- Other payroll deductions
A housing payment that appears reasonable relative to gross income may feel much more expensive when compared with the money actually available for everyday spending.
Rent Can Be Predictable but Still Expensive
Rent has one major advantage for household budgeting: many renters know their basic housing payment in advance.
But rent can also increase.
A family that is comfortable with its current rent may face financial pressure after a substantial increase at renewal.
Renters should therefore avoid assuming that today’s housing cost will remain unchanged indefinitely.
When possible, leave some room in the budget for future increases.
Homeownership Has Hidden Costs
Owning a home can create a sense of financial security, but the mortgage payment is only part of the expense.
A homeowner may eventually face:
- A leaking roof
- Broken appliances
- Plumbing problems
- Electrical repairs
- Heating or cooling failures
- Pest problems
- Landscaping expenses
- Exterior maintenance
Some of these costs can be expensive.
A family that uses every available dollar for the down payment and mortgage may find itself financially vulnerable when the first major repair arrives.
Maintenance Should Be Part of the Budget
Home maintenance is easier to manage when it is treated as a regular financial obligation rather than an unexpected emergency.
A family can create a dedicated home-maintenance fund and contribute to it regularly.
The appropriate amount depends on factors such as:
- Property age
- Home size
- Condition
- Climate
- Major systems
- Local labor costs
Older properties may require more financial preparation than newer ones.
Property Taxes Can Change the Equation
Property taxes are another important housing expense for homeowners.
Tax rates and property assessments vary by location.
They can also change over time.
A home with a seemingly affordable mortgage can become more expensive when property taxes are high.
When comparing homes, families should look at the total annual property tax rather than focusing only on the purchase price.
Insurance Is Another Recurring Expense
Homeowners insurance protects against certain covered losses, but the premium becomes part of the household’s ongoing housing expense.
Insurance costs can vary depending on:
- Location
- Property value
- Construction
- Coverage
- Claims history
- Local weather risks
Some properties may also require additional coverage for specific risks.
Renters have insurance costs too, although these are typically much lower than homeowners insurance.
Utilities Can Vary Dramatically
A home’s utility costs can have a significant effect on family finances.
Expenses may include:
- Electricity
- Natural gas
- Water
- Sewer
- Trash
- Heating
- Cooling
- Internet
Two homes with the same rent or mortgage can have very different total monthly costs.
A large, poorly insulated house may cost considerably more to heat and cool than a smaller, energy-efficient property.
Housing Size Affects the Budget
A larger home generally means more than a larger mortgage or rent payment.
It can also mean:
- Higher utility bills
- More furniture
- More maintenance
- Higher insurance
- Greater property taxes
- More cleaning
- More landscaping
- More expensive repairs
This is why families should think about the total cost of space, rather than simply asking whether they can afford the monthly payment.
Location Can Be More Important Than Square Footage
A cheaper home farther from work may not actually be cheaper for the family.
Longer commutes can increase:
- Fuel costs
- Vehicle maintenance
- Insurance
- Public transportation expenses
- Travel time
A more expensive home closer to work or school could potentially reduce transportation costs.
This is why housing and transportation should often be considered together.
Childcare and School Costs Can Influence Housing Decisions
Families with children may need to consider how their housing location affects childcare and education expenses.
A home closer to a childcare provider could reduce commuting time.
A location may also influence school-related transportation and other costs.
Families should evaluate these factors alongside rent or mortgage payments rather than treating housing as an isolated expense.
Housing costs can also compete directly with education savings. Families planning ahead should consider how to plan and save for education costs when deciding how much of their income can reasonably be committed to housing.
Housing Can Affect Family Savings
One of the first financial goals affected by expensive housing is often savings.
Suppose a family has $500 available each month after all regular expenses.
If housing costs rise by $300, only $200 remains.
That means the family may still be able to pay its bills but has less capacity to build:
- An emergency fund
- Retirement savings
- College savings
- A down payment
- Investment accounts
Over several years, this difference can become substantial.
Housing Costs Can Slow Debt Repayment
Families carrying credit-card balances, personal loans or other debt may also find that expensive housing slows their progress.
Suppose a household has $600 available each month for extra debt payments.
A $300 increase in housing costs could reduce that amount to $300.
The debt may still be manageable, but it will take longer to eliminate.
The additional interest paid over time can further increase the financial cost.
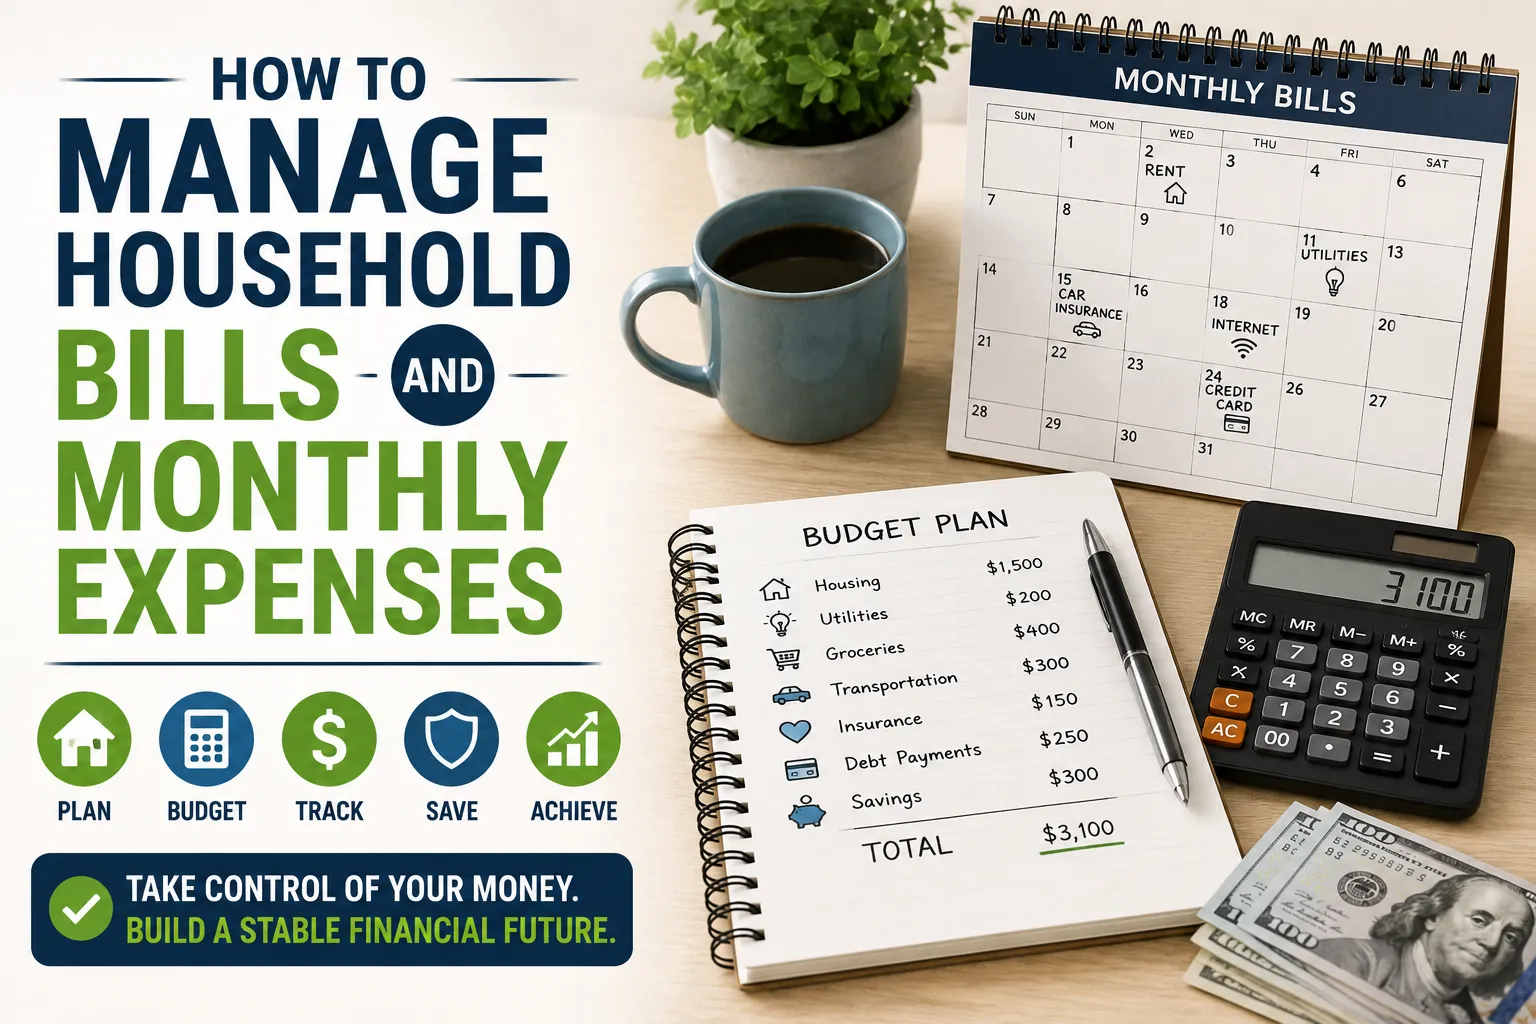
Housing also has to compete with everyday household obligations. Families should understand how to manage household bills and monthly expenses so that housing does not crowd out other necessary spending.
Housing Can Influence Retirement Planning
Housing costs remain important even after children leave home and other expenses change.
A large mortgage payment later in life can create financial pressure during retirement.
For this reason, families should consider how today’s housing decision fits into long-term plans.
Questions worth asking include:
- When will the mortgage be paid off?
- How much retirement income will be needed?
- Will the property require significant maintenance?
- Is downsizing a possibility?
- Are property taxes and insurance likely to remain manageable?
A home can be an important asset, but it also creates ongoing expenses.
Housing Decisions Affect Financial Flexibility
Financial flexibility means having room to respond when life changes.
A household with manageable housing costs may be better positioned to handle:
- Job loss
- Medical expenses
- A new child
- Career changes
- Economic downturns
- Family emergencies
- Major repairs
A household with very high fixed expenses has fewer options.
This is one reason conservative housing decisions can be valuable even when a larger home is technically affordable.
Emergency Funds Become More Important for Homeowners
Homeowners face expenses that renters may not encounter.
A broken water heater, damaged roof or failed HVAC system can create a large bill.
An emergency fund can prevent families from relying entirely on credit cards or high-cost borrowing when these events occur.
The exact emergency-fund target depends on the household, but families with homeownership responsibilities may want to account specifically for property-related emergencies.
Housing Can Influence Career Choices
A high mortgage or rent payment can affect employment decisions.
Someone with relatively low living costs may have more freedom to:
- Change careers
- Start a business
- Reduce working hours
- Take a lower-paying but more fulfilling job
- Return to school
A household with a large monthly housing obligation may have less flexibility to make those changes.
This is an often-overlooked cost of expensive housing.
Housing Can Affect Family Stress
Money and housing are closely connected to household stress.
When a large share of income goes toward housing, families may argue more frequently about:
- Spending
- Debt
- Saving
- Childcare
- Vacations
- Home repairs
- Lifestyle choices
A home should provide security and comfort.
If the cost of maintaining it consistently creates financial anxiety, the property may be too expensive for the household’s circumstances.
Don’t Forget the Cost of Furnishing a Home
Moving into a larger home can create another financial challenge.
More rooms often create pressure to buy:
- Sofas
- Beds
- Tables
- Desks
- Curtains
- Rugs
- Lighting
- Appliances
- Decorations
Families can easily spend thousands of dollars trying to furnish an entire property immediately.
There is no requirement to fill every room on the first day.
Buying gradually can protect the household budget.
Renovations Can Expand Housing Costs
Home improvement projects can be useful, but they can also become a major source of financial pressure.
Projects often cost more than initially expected because of:
- Labor
- Materials
- Permits
- Design changes
- Unexpected structural problems
- Delays
Before starting a renovation, families should consider whether the project is necessary, optional or simply desirable.
A project that can wait may be better postponed until the household has sufficient cash.
Home Equity Is Not the Same as Cash
Homeowners sometimes feel financially secure because their property has increased in value.
But home equity is not the same as money sitting in a bank account.
Accessing equity may require:
- Selling the property
- Refinancing
- Taking out a home-equity loan
- Using a home-equity line of credit
These options have costs and risks.
A family should therefore maintain liquid savings even if it has substantial home equity.
Housing Costs Can Influence Net Worth
Housing can contribute to wealth building when property values rise and mortgage debt is paid down.
But appreciation is not guaranteed.
Homeownership also comes with transaction costs, maintenance expenses, taxes and insurance.
A family should not assume that buying a home automatically guarantees financial success.
The financial outcome depends on factors such as:
- Purchase price
- Financing
- Interest costs
- Maintenance
- Local property values
- Length of ownership
- Selling costs
Renting Does Not Mean “Throwing Money Away”
Rent provides a housing service.
In exchange for rent, the tenant receives a place to live without being responsible for many ownership-related costs.
The landlord generally handles major structural repairs and property ownership expenses.
Renting can also provide flexibility for people who may move for work or other reasons.
The financial comparison between renting and buying is more complicated than simply comparing rent with a mortgage payment.
Buying Can Build Equity
One potential advantage of homeownership is that part of each mortgage payment may go toward reducing the loan principal.
Over time, this can increase the homeowner’s equity.
But early mortgage payments can contain a relatively large share of interest, depending on the loan structure.
Homeowners should therefore understand how their mortgage payment is divided.
Interest Rates Can Change Housing Affordability
For buyers using a mortgage, interest rates have a major effect on monthly payments.
Two families purchasing identical homes at different rates can have very different monthly costs.
Higher rates can reduce the amount a household can comfortably borrow.
They can also increase the total amount paid over the life of the mortgage.
This is why families should avoid choosing a home based solely on the purchase price.
Adjustable Payments Require Extra Caution
Some housing arrangements can have payments that change over time.
Mortgage structures with adjustable interest rates can create uncertainty about future payments.
Renters may also face increases when leases are renewed.
Families with limited financial flexibility should be particularly cautious about housing arrangements where future costs could rise significantly.
Housing Costs Can Affect Everyday Spending
When housing takes up a large share of income, families often compensate by cutting other expenses.
The first cuts may be discretionary:
- Restaurants
- Entertainment
- Travel
- Hobbies
Eventually, however, households may begin reducing spending on areas that are harder to cut, such as:
- Food quality
- Healthcare
- Education
- Vehicle maintenance
- Retirement contributions
This is a sign that housing costs may be putting too much pressure on the budget.
A Housing Budget Should Include Savings
Savings should not simply be whatever is left after paying for housing and other bills.
Ideally, savings should be treated as an intentional part of the household budget.
Depending on the family’s goals, this could include:
- Emergency savings
- Retirement
- Education
- Short-term goals
- Home maintenance
- Investments
If housing costs make consistent saving impossible, it is worth reassessing the housing arrangement.
Families Should Review Housing Costs Regularly
A housing budget should not be created once and forgotten.
Review it when major circumstances change, such as:
- A new job
- A pay increase
- A pay cut
- Marriage
- Divorce
- A new child
- Children leaving home
- Major debt repayment
- Moving
- Refinancing
- Retirement
A home that was affordable five years ago may not fit the household’s current financial priorities.
How to Reduce the Impact of Housing Costs
Families have several options when housing becomes too expensive.
Reduce other housing-related expenses
Look for opportunities to reduce:
- Energy use
- Insurance costs
- Unnecessary subscriptions
- Maintenance expenses
Consider refinancing when appropriate
Homeowners may be able to reduce borrowing costs under certain market conditions, although refinancing comes with fees and is not always beneficial.
Rent out unused space where appropriate
Some homeowners may consider renting a room or separate unit, subject to local laws, mortgage requirements, insurance rules and personal preferences.
Downsize
Moving to a smaller property can reduce housing and maintenance costs.
Move to a lower-cost area
If employment and family circumstances allow, relocation may significantly reduce housing expenses.
Improve energy efficiency
Efficient appliances, insulation and other improvements can reduce utility costs over time.
Avoid Making Housing Decisions Based on Appearances
A larger house can look like a sign of financial success.
But a home should be evaluated according to what it does for the family’s finances and lifestyle.
A smaller house with manageable expenses may provide more financial freedom than a large house that consumes most of the household’s income.
The objective is not to maximize square footage.
It is to create a sustainable living arrangement.
Think About Total Cost Instead of Monthly Payment
When comparing homes, calculate the estimated annual cost.
For example:
Mortgage: $1,800 × 12 = $21,600
Property taxes: $4,800
Insurance: $1,800
HOA: $1,200
Maintenance reserve: $2,400
Estimated annual housing cost:
$21,600 + $4,800 + $1,800 + $1,200 + $2,400 = $31,800
That works out to an average of:
$31,800 ÷ 12 = $2,650 per month
The advertised mortgage payment of $1,800 therefore understates the likely total housing cost.
Create a Housing Stress Test
A useful household exercise is to calculate what happens if housing costs rise.
Suppose your current total housing cost is $2,000 per month.
Now test:
$2,200
$2,400
$2,600
Could the family still pay its bills and save?
This exercise can reveal how much financial flexibility exists.
It is particularly useful when considering a purchase because it can show whether a seemingly affordable property would leave too little room for unexpected costs.
Ask Whether the Home Supports Your Goals
A good housing decision should support your broader financial goals.
Ask:
- Can we save for emergencies?
- Can we continue retirement contributions?
- Can we pay down debt?
- Can we afford childcare?
- Can we handle repairs?
- Can we enjoy some discretionary spending?
- Can we manage a temporary income reduction?
If the answer to most of these questions is yes, the housing arrangement is more likely to be sustainable.
Housing Is Both a Need and a Financial Decision
Housing will always be a necessary expense, but families have choices about how much they spend on it.
The goal is not necessarily to spend as little as possible.
A safe neighborhood, suitable space, convenient location and comfortable home can all provide significant value.
The challenge is finding a balance between those benefits and the household’s financial capacity.
A Sustainable Home Budget Creates More Choices
Housing affects nearly every part of family finances because it is one of the largest and least flexible expenses in the household budget.
A high housing payment can reduce savings, delay debt repayment, limit career flexibility and make unexpected expenses more difficult to absorb. A manageable housing cost can have the opposite effect, giving families more room to build savings, invest, handle emergencies and pursue other goals.
The most useful approach is to look beyond rent or the mortgage payment and calculate the true cost of living in the home.
That means accounting for taxes, insurance, utilities, maintenance, transportation, repairs and the financial goals that continue after the housing payment is made.
The right home is not necessarily the biggest or most expensive one a family can qualify for. It is the one that provides a comfortable place to live while leaving enough financial breathing room to save, prepare for the unexpected and build the future the household wants.