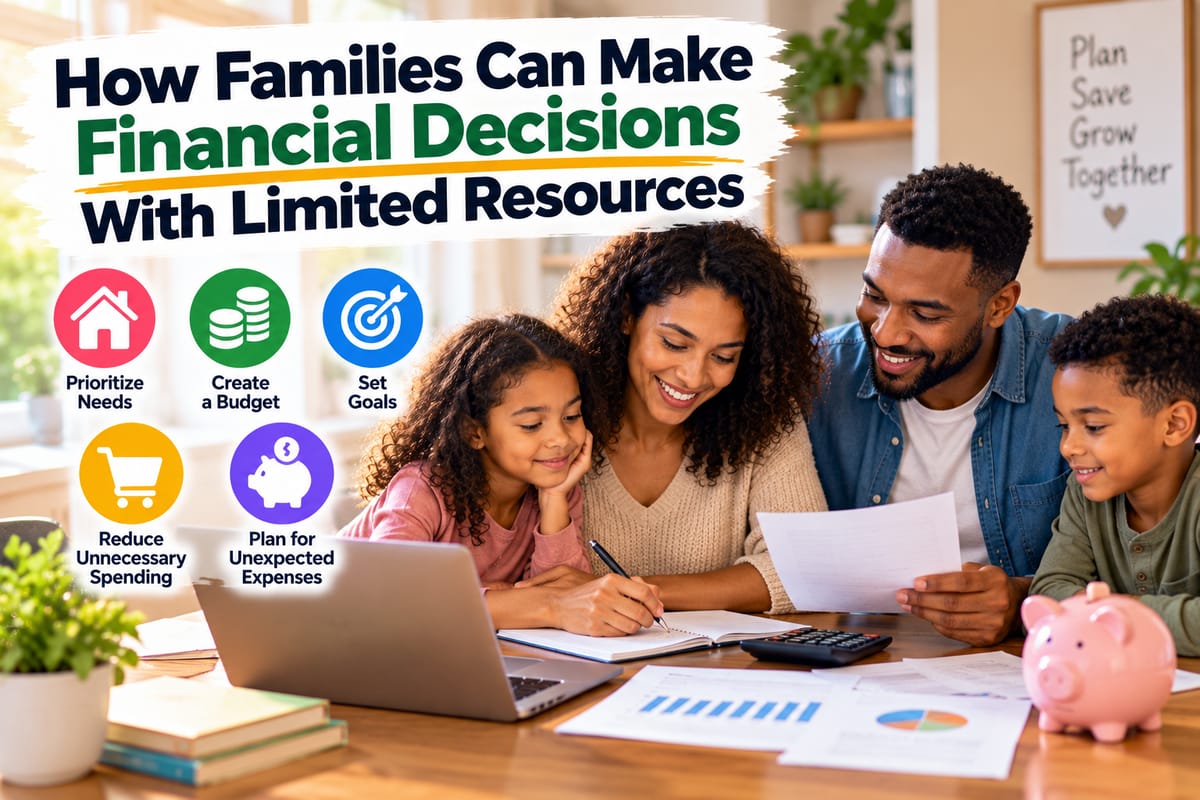
How Families Can Make Financial Decisions With Limited Resources
Families rarely have unlimited money, time, or financial flexibility. Even households with stable incomes can face periods when several priorities compete for the same limited resources. Housing, food, transportation, education, healthcare, debt payments, savings, and everyday expenses can all demand attention at the same time.
Making financial decisions with limited resources is therefore less about finding a perfect solution and more about deciding what matters most, understanding available options, and using money deliberately.
A family does not need to eliminate every expense or avoid spending altogether. Instead, it can create a practical decision-making process that helps protect essential needs, manage risks, and make progress toward important financial goals.
What Does It Mean to Have Limited Financial Resources?
Limited resources do not necessarily mean that a family has a very low income. A household can have a reasonable income and still experience financial constraints when its obligations consume most of its available money.
Resources can be limited by:
- Household income
- High housing costs
- Debt payments
- Childcare expenses
- Healthcare costs
- Transportation needs
- Rising food prices
- Irregular expenses
- Limited savings
- Unpredictable income
- Unexpected emergencies
Time and attention are also resources. A family may technically have enough income but struggle to manage its finances because bills, accounts, subscriptions, debt, and spending decisions have become too complicated.
The first step is recognizing that financial decisions involve trade-offs.
When money cannot cover every desirable goal at once, choosing one priority usually means delaying, reducing, or changing another.
Start With the Family’s Essential Needs
When resources are tight, families generally need to distinguish between essential expenses and expenses that can be postponed or reduced.
Essential expenses commonly include:
- Housing
- Basic food
- Utilities
- Transportation required for work or school
- Necessary healthcare
- Minimum debt payments
- Essential insurance
- Childcare required for employment
This does not mean every expense in these categories is automatically unavoidable. There may still be opportunities to reduce costs.
For example, a family may need transportation but have several choices concerning the type of vehicle, maintenance schedule, insurance coverage, or commuting arrangements.
The important distinction is between the need itself and the particular way the household currently pays for that need.
Understand the Difference Between Needs and Wants
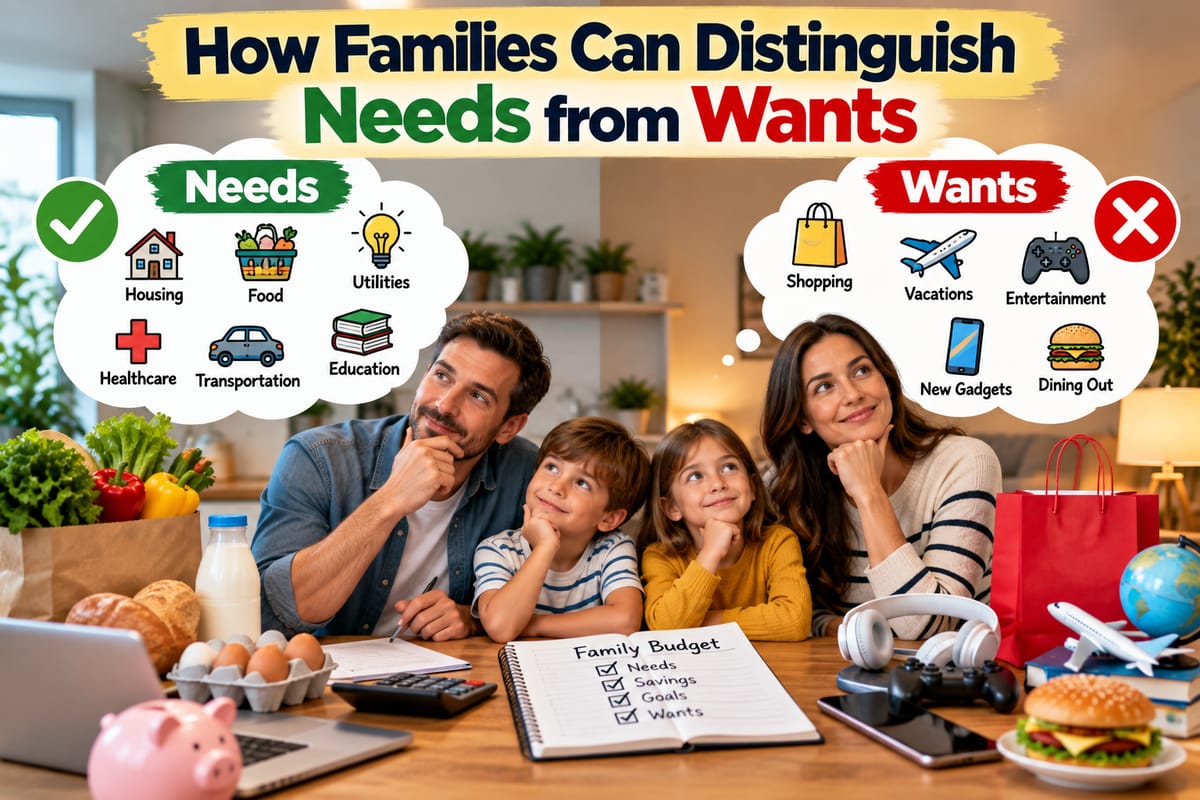
One of the simplest ways to improve financial decision-making is to distinguish between needs, wants, and goals.
Needs
Needs are expenses required to maintain basic household functioning, health, safety, or essential responsibilities.
Wants
Wants improve comfort, convenience, entertainment, or lifestyle but can often be delayed or reduced.
Goals
Goals are things the family deliberately wants to accomplish financially, such as building savings, paying off debt, buying a home, funding education, or preparing for retirement.
The categories can change depending on circumstances.
For example, a reliable internet connection might be a convenience for one household but an essential resource for another family whose members work or study from home.
The objective is not to label every purchase permanently. It is to understand what each expense means for the household’s current situation.
Know How Much Money Is Actually Available
Financial decisions become much easier when families know their actual available cash.
A household should consider:
Income − Essential expenses − Required debt payments − Planned savings = Available discretionary money
This does not need to be calculated perfectly down to the last cent every month. The purpose is to establish a realistic picture of what remains after important obligations are covered.
Income can include:
- Salaries
- Wages
- Self-employment income
- Business income
- Benefits
- Rental income
- Investment income
- Other recurring sources
If income changes from month to month, families should work with conservative estimates rather than assuming the highest possible income will continue.
Build a Family Budget
A budget gives a household a framework for deciding where its limited resources should go.
A practical budget can organize money into categories such as:
| Category | Examples |
|---|---|
| Housing | Rent, mortgage, property costs |
| Food | Groceries and essential meals |
| Utilities | Electricity, water, internet |
| Transportation | Fuel, fares, maintenance |
| Healthcare | Medical expenses and insurance |
| Debt | Required payments and extra repayment |
| Savings | Emergency fund and other goals |
| Children | School, childcare, activities |
| Personal | Clothing and personal expenses |
| Flexible spending | Entertainment and discretionary purchases |
Families can learn more about creating a workable household spending plan through How to Build a Family Budget.
A budget is not merely a list of restrictions. It is a decision-making tool that shows where limited money is going and where adjustments may be possible.
Prioritize Financial Goals
A household may have several legitimate financial goals at the same time.
For example, a family might want to:
- Build an emergency fund
- Pay off credit card debt
- Replace an aging vehicle
- Save for education
- Make a home repair
- Save for retirement
- Take a vacation
- Start a business
Trying to fund everything equally can spread limited resources too thin.
Instead, families can establish a priority order.
One practical approach is to consider:
- What is essential?
- What is urgent?
- What prevents serious financial damage?
- What reduces future costs?
- What supports long-term security?
- What can safely be delayed?
A detailed framework for organizing household priorities can be found in How Families Can Set, Prioritize and Achieve Household Financial Goals.
Consider Consequences Before Making a Financial Decision
A financial decision should not be judged only by its immediate price.
Families can ask what happens after the purchase or decision.
For example, buying an inexpensive appliance might appear attractive, but if it is unreliable and needs frequent repairs, the total cost could eventually exceed that of a more durable alternative.
Similarly, delaying maintenance may save money today while creating a larger expense later.
Before making a significant decision, consider:
- Upfront cost
- Ongoing cost
- Maintenance
- Financing charges
- Opportunity cost
- Risk of failure
- Expected lifespan
- Effect on other household goals
Thinking beyond the initial price can lead to better resource allocation.
Separate Fixed and Flexible Expenses
Some household expenses are difficult to change quickly.
These may include:
- Rent
- Mortgage payments
- Insurance premiums
- Certain debt payments
- School fees
- Long-term contracts
Other expenses can usually be adjusted more easily.
These may include:
- Restaurants
- Entertainment
- Clothing
- Subscriptions
- Travel
- Some grocery choices
- Nonessential shopping
When resources become limited, flexible expenses are often the first place to look for adjustments.
However, families should avoid assuming that every small discretionary purchase is the main cause of financial pressure. Large recurring expenses can have a much greater effect on a household’s finances.
Look for the Biggest Opportunities to Save
Cutting five small expenses may feel productive, but changing one large recurring expense can sometimes have a much greater effect.
For example, a household might examine:
- Housing costs
- Transportation expenses
- Insurance
- Debt interest
- Phone plans
- Internet plans
- Major subscriptions
- Grocery habits
- Energy consumption
Suppose a family saves a small amount on several subscriptions but continues paying a high interest rate on expensive debt. Redirecting attention toward the debt may produce a larger financial benefit.
This is why families should examine their overall spending rather than focusing exclusively on minor purchases.
Reduce Unnecessary Spending Without Eliminating Everything
Reducing household spending does not mean eliminating every enjoyable activity.
A sustainable approach focuses on spending that provides relatively little value compared with its cost.
Families can review:
- Unused subscriptions
- Duplicate services
- Frequent convenience purchases
- Food waste
- Impulse shopping
- Unused memberships
- Unnecessary fees
- Purchases made without comparison
- Recurring services that are rarely used
More ideas for identifying and reducing low-value expenses are covered in How to Reduce Unnecessary Household Spending.
The goal is to create more financial room while preserving spending that genuinely matters to the household.
Plan for Irregular Expenses
One reason household finances can feel unpredictable is that not every expense arrives every month.
Examples include:
- School expenses
- Insurance premiums
- Vehicle repairs
- Home maintenance
- Annual memberships
- Holiday spending
- Medical expenses
- Property taxes
- Professional fees
- Appliance replacement
These expenses are not necessarily emergencies simply because they do not occur monthly.
Families can estimate their annual cost and divide it across the year.
For example, if a household expects to spend $1,200 on irregular expenses over a year, setting aside approximately $100 per month creates a fund for those future costs.
This approach can make large expenses easier to absorb.
Families can explore this approach further in How Families Can Budget for Irregular Expenses.
Use Sinking Funds for Known Future Costs
A sinking fund is money set aside gradually for a specific future expense.
For example:
Expected annual car maintenance: $600
Monthly amount to set aside: $50
After 12 months, the household has approximately $600 available for that purpose.
Sinking funds can be useful for expenses that are predictable but not monthly.
They can reduce the need to rely on credit when an expected expense eventually arrives.
Common sinking-fund categories include:
- Car maintenance
- Home repairs
- School costs
- Holidays
- Annual insurance
- Medical expenses
- Electronics replacement
- Birthdays and celebrations
Create an Emergency Fund
Not every financial problem can be predicted.
An emergency fund provides a reserve for unexpected events such as:
- Job loss
- Major repairs
- Urgent medical expenses
- Emergency travel
- Essential equipment replacement
The appropriate amount varies by household.
A family with stable income and relatively predictable expenses may have different needs from a household with variable income or limited employment security.
When resources are extremely limited, even building a small emergency reserve can create some breathing room.
The key is to treat emergency savings as a financial priority rather than money that is available for routine discretionary spending.
Make Decisions Based on Total Household Impact
A purchase should be evaluated in the context of the entire household.
For example, one family member may want a new vehicle because the current one is inconvenient. But the decision could affect:
- Monthly payments
- Insurance
- Fuel
- Maintenance
- Savings
- Debt repayment
- Other family goals
A household should therefore ask:
How will this decision affect the rest of our financial plan?
This question helps prevent isolated decisions from undermining larger priorities.
Compare Alternatives Before Spending
When resources are limited, comparison shopping can make a meaningful difference.
For major purchases, families can compare:
- Purchase price
- Quality
- Warranty
- Maintenance
- Energy consumption
- Financing terms
- Expected lifespan
- Replacement costs
The cheapest option is not always the least expensive over time.
At the same time, the most expensive option is not automatically the best value.
The objective is to find an option that meets the household’s needs at an acceptable total cost.
Use Delayed Decisions for Nonessential Purchases
A useful strategy for discretionary purchases is to create a waiting period.
For example, a family might wait:
- 24 hours for small purchases
- Several days for moderately expensive purchases
- Several weeks for major discretionary purchases
During the waiting period, ask:
- Do we still need it?
- Is it already available at home?
- Does it support an important goal?
- Can we pay for it without borrowing?
- Is there a lower-cost alternative?
- Will we still value it several months from now?
This approach can reduce impulse purchases without requiring a household to ban discretionary spending entirely.
Communicate Before Making Major Decisions
Financial decisions affect everyone in a household, especially when resources are limited.
Partners or other household decision-makers should discuss major expenses before committing money.
Useful topics include:
- Current income
- Upcoming expenses
- Debt
- Savings
- Financial priorities
- Children’s needs
- Major purchases
- Changes in employment
- Long-term goals
The purpose is not for every household member to agree on every purchase.
Instead, communication helps prevent surprises and makes it easier to coordinate limited resources.
Involve Children Appropriately
Children do not need to know every detail of a family’s financial situation, but age-appropriate conversations about money can help them understand trade-offs.
Parents can explain concepts such as:
- Needs versus wants
- Saving
- Planning
- Delayed gratification
- Comparing prices
- Making choices within a budget
For example, instead of simply saying that a purchase is too expensive, a parent could explain that the family is saving money for another priority.
This teaches children that financial decisions often involve choosing between competing uses of limited resources.
Avoid Making Every Decision Based on Price Alone
Price is important, but it is not the only consideration.
A low-cost product can become expensive if it needs frequent replacement.
Likewise, a slightly more expensive service may save money if it lasts longer or reduces maintenance costs.
Families should consider value, not simply price.
A useful comparison is:
Total cost of ownership = purchase price + ongoing costs + maintenance + financing − useful residual value
The exact calculation will vary depending on the purchase, but the principle is useful across many household decisions.
Consider Opportunity Cost
Every financial decision has an opportunity cost.
If a family spends $500 on one purchase, that $500 cannot simultaneously be used for another purpose.
The money might otherwise have gone toward:
- Debt repayment
- Emergency savings
- Education
- Home maintenance
- Transportation
- Retirement
- Another planned purchase
This does not mean spending $500 is necessarily wrong. It means the household should understand what it is giving up by choosing that purchase.
Thinking in terms of opportunity cost can make priorities clearer.
Be Careful With Debt
Borrowing can help families manage important expenses, but debt also commits future income.
Before taking on new debt, consider:
- Interest rate
- Fees
- Monthly payment
- Repayment period
- Total amount repaid
- Effect on other financial goals
- Ability to continue making payments if income falls
A purchase that appears affordable based only on the monthly payment may be considerably more expensive over the full repayment period.
Families with limited resources should be particularly careful about using high-cost debt for discretionary purchases.
Distinguish Emergencies From Inconveniences
When something unexpected happens, it can feel urgent even when it is not financially critical.
For example, replacing a working but outdated electronic device may feel necessary because a newer model is available.
A medical emergency, major vehicle failure, or sudden loss of essential income is different.
Before spending emergency savings or taking on debt, ask:
Is this truly urgent, or is it simply inconvenient?
This distinction can help preserve limited financial resources for situations that genuinely require immediate action.
Review Recurring Expenses Regularly
Household finances can gradually become more expensive without any single dramatic decision.
A subscription might be added one month. An insurance premium may increase. A service may become more expensive. A family member might stop using a membership.
Over time, these small changes can consume significant amounts of money.
A periodic review can examine:
- Subscriptions
- Insurance
- Banking fees
- Phone services
- Internet
- Memberships
- Utilities
- Debt interest
- Recurring deliveries
The goal is not to eliminate everything. It is to ensure that recurring expenses still provide sufficient value.
Make Room for Flexibility
A financial plan should not be so rigid that one unexpected expense destroys it.
Families can build flexibility by maintaining:
- A small cash reserve
- Emergency savings
- Flexible spending categories
- Sinking funds
- Multiple options for major purchases
- Conservative income assumptions
Flexibility is especially important for households with irregular or unpredictable income.
Instead of allocating every available dollar to fixed commitments, leaving some room for unexpected costs can make the overall plan more resilient.
Use a Simple Decision Framework
When faced with a financial choice, families can work through a simple sequence.
1. Define the Decision
What exactly needs to be decided?
2. Identify the Need
Why is the decision necessary?
3. Determine the Cost
How much will it cost initially and over time?
4. Consider Alternatives
Are there cheaper, delayed, shared, repaired, borrowed, or used options?
5. Check the Budget
Can the household afford it without undermining essential expenses?
6. Consider the Opportunity Cost
What other goal would receive less money if this decision is made?
7. Evaluate the Risk
What happens if income falls or the expense becomes larger than expected?
8. Decide and Review
Make the decision, then evaluate later whether it produced the expected value.
This process can be applied to purchases ranging from household appliances to vehicles, education expenses, travel, and home improvements.
Example of a Family Making a Difficult Decision
Imagine a household has $1,000 available after covering its essential monthly expenses.
The family is considering three priorities:
- $600 for an urgent vehicle repair
- $500 toward an existing debt
- $300 toward a planned family event
The household cannot fully fund all three.
Instead of dividing the money equally, the family can examine the consequences.
If the vehicle is necessary for employment, repairing it may protect the family’s ability to earn income.
The debt payment may reduce future interest costs.
The family event may be meaningful but potentially easier to postpone or scale back.
The eventual decision depends on the family’s specific circumstances, but the process illustrates an important principle: limited resources require priorities based on consequences, urgency, and long-term needs.
What Families Should Avoid
Financial pressure can lead to decisions that provide short-term relief while creating larger problems later.
Common mistakes include:
Ignoring Small Problems
A minor financial issue can become expensive if it is repeatedly postponed.
Relying on Credit for Routine Spending
Using debt to cover ordinary expenses can create a cycle in which future income is increasingly committed to past purchases.
Making Decisions Without Communication
One major purchase can disrupt an entire household budget when other family members were not aware of it.
Budgeting With Unrealistic Income
Assuming that overtime, bonuses, commissions, or occasional income will always arrive can make a budget fragile.
Cutting Everything at Once
Extremely restrictive spending plans may be difficult to maintain and can lead to frustration.
Focusing Only on Short-Term Savings
A decision that saves money today may create higher costs later.
Adjust the Plan When Circumstances Change
A household budget is not a permanent contract.
Financial circumstances can change because of:
- A new job
- Job loss
- A new child
- Moving
- Higher rent
- Lower income
- New debt
- Medical expenses
- School costs
- Changes in transportation needs
When circumstances change, families should revisit their priorities instead of assuming the old plan still works.
A financial plan should reflect current reality.
Focus on Progress Rather Than Perfection
Families with limited resources may not be able to make every financially ideal decision.
Unexpected expenses happen. Budgets get exceeded. Income changes. Priorities shift.
The goal is therefore not perfection.
A useful financial system should help a household make better decisions more consistently.
That might mean saving a small amount instead of nothing, reducing one unnecessary recurring expense, paying a little extra toward debt, planning for an upcoming annual bill, or avoiding a purchase that would create financial pressure.
Small improvements can become meaningful when repeated over time.
A Practical Monthly Financial Routine
Families can simplify financial decision-making by establishing a regular routine.
Review Income
Determine how much money is expected during the coming month.
Review Essential Expenses
Identify housing, food, utilities, transportation, healthcare, and required debt payments.
Check Upcoming Irregular Costs
Look ahead for school expenses, repairs, annual bills, celebrations, and other known costs.
Fund Priority Goals
Direct available money toward the household’s most important current goals.
Review Discretionary Spending
Identify areas that can be reduced if necessary.
Check Savings
Confirm that emergency and sinking-fund contributions remain realistic.
Discuss Major Decisions
Talk about significant purchases or changes before committing household resources.
This process does not need to take hours. A consistent review can provide a much clearer picture of where the family’s money is going.
Making Limited Resources Work Harder
When resources are limited, families cannot always increase their income immediately. They can, however, improve how they allocate what they already have.
That means protecting essential needs, prioritizing important goals, preparing for irregular costs, comparing alternatives, reducing low-value spending, communicating about major decisions, and considering both short-term and long-term consequences.
The most useful financial system is rarely the one with the most complicated rules. It is the one a family can understand, maintain, and adjust as circumstances change.
By treating household money as a limited resource that needs to be allocated intentionally, families can make clearer decisions even when there is not enough money to accomplish everything at once. The objective is not to eliminate every financial constraint, but to direct available resources toward the needs, priorities, and goals that matter most.